US credit spreads eased on October 2 after widening beyond the weakest borrowers
US corporate credit spreads eased on October 2 after widening across investment-grade and high-yield debt between late September and early October, raising questions about potential impacts on Bitcoin and institutional risk appetite.

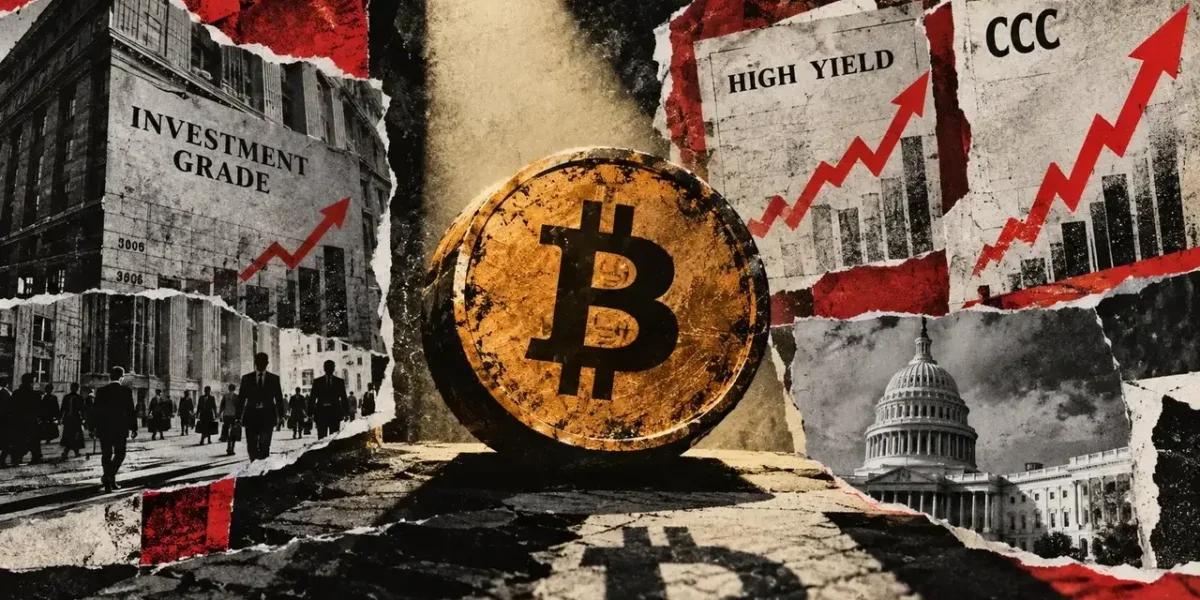
Between September 25 and October 1, US corporate credit spreads expanded past vulnerable borrowers, introducing a broader test to see if stricter financing conditions and lower institutional risk appetite might weigh on Bitcoin. While investment-grade bonds experienced a modest lift, the most substantial gains remained concentrated in debt rated CCC and below.
These option-adjusted spreads track the premium demanded over a Treasury curve, reflecting investors’ desire for extra compensation to hold corporate debt. Total borrowing costs for any given entity also factor in the Treasury component.
Specifically, the ICE BofA CCC credit spread grew by 87 basis points, moving from 11.28% to 12.15%. Over that same period, the broader high-yield spread climbed 31 basis points from 2.93% to 3.24%, and the investment-grade corporate spread ticked up 5 basis points from 0.81% to 0.86%.
These comparisons rely on daily closing figures from September 25 and October 1, 2026. Data updates published by FRED on October 5 introduced readings for October 2, showing CCC-and-lower debt at 12.02%, broad high yield at 3.10%, and investment-grade debt at 0.85%. Although all three retreated from their October 1 peaks, they remained higher than their September 25 marks.
The movement in investment-grade debt offers the clearest proof that repricing stretched further than the lowest-rated obligations. Because CCC-and-lower bonds are already factored into the broader high-yield index, those two increases represent overlapping data points, painting a picture of widespread but uneven pressure.
How credit spreads could reach Bitcoin
Transmission to Bitcoin would rely on how shifts in credit repricing alter the cost of capital and overall risk appetite. Should financing become costlier, leveraged traders might be forced to unwind positions, while institutions could scale back their crypto exposure as they reevaluate risk tolerances across portfolios.
A similar dynamic is outlined in a 2023 IMF working paper titled The Crypto Cycle and US Monetary Policy. Historical examination within the paper indicates that monetary tightening can elevate capital expenses, push crypto investors to cut back on leverage, and depress aggregate cryptocurrency prices, with institutional involvement serving as a transmission channel.
While that paper focuses on historical monetary-policy shocks, current metrics track corporate credit premiums. Applying this framework to the present situation remains conditional; while the spread data confirms credit repricing, ongoing Bitcoin selling and its direct catalysts have not been definitively established.
The Chicago Fed National Financial Conditions Index offers a wider benchmark, registering -0.548 for the week ending September 25 in a release published on September 30. This negative figure points to financial conditions that were looser than average, though the reading predates the latest spread calculations.
Moving forward, the primary test is whether this widening trend continues past the most vulnerable borrowers, aligning with deteriorating broad financial conditions and softer demand for Bitcoin. Such conditions would bolster the argument that institutional risk-taking faces a wider squeeze. Conversely, narrowing spreads alongside strong Bitcoin demand would weaken that thesis.
Frequently Asked Questions
01What are corporate credit spreads?
Corporate credit spreads measure the additional yield investors demand to hold corporate debt over risk-free Treasury curves, reflecting the perceived credit risk of borrowers.
02How do credit spreads affect Bitcoin?
Wider spreads can signal tighter financing conditions and higher capital costs, which may prompt leveraged investors and institutions to reduce exposure to risk assets like Bitcoin.
03Did credit spreads continue to widen through October 2?
After rising between September 25 and October 1, credit spreads for investment-grade, high-yield, and CCC-rated debt eased slightly on October 2, though they remained above their September 25 levels.