US bank group taps Quant for tokenized deposits, but QNT’s role is left in doubt
The Clearing House selected Quant to provide software for a tokenized bank deposit network, but the direct requirement and role of the QNT utility token remain unconfirmed, sparking market volatility.

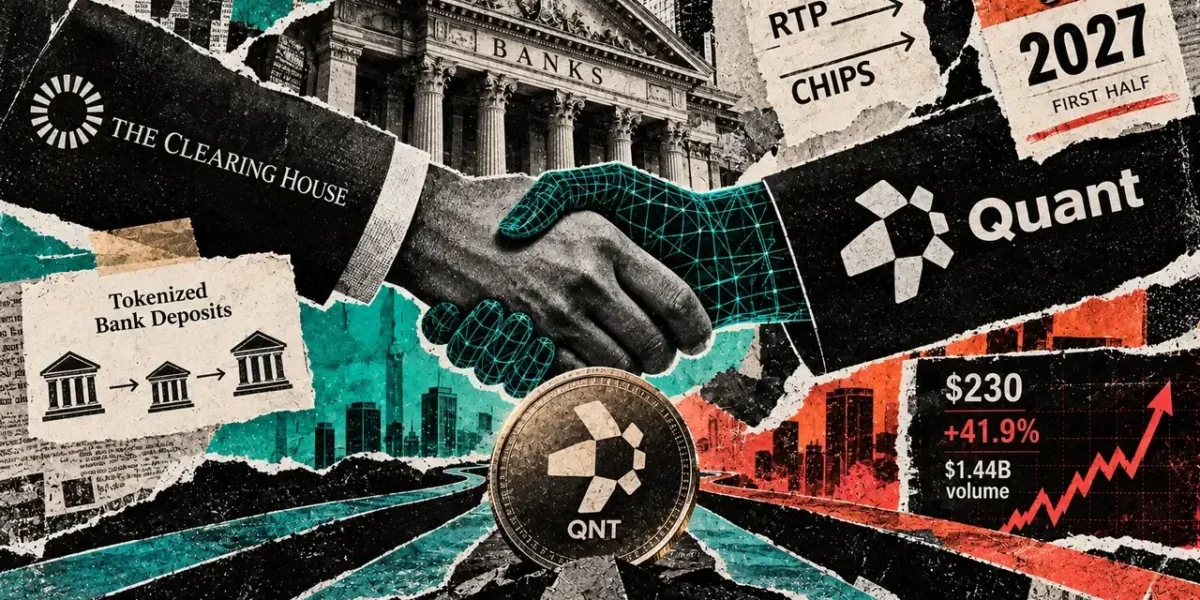
The Clearing House, a bank-owned US payments operator, has enlisted Quant to provide software for an upcoming network designed for tokenized bank deposits.
While the September 24 agreement secures Quant a position in facilitating the transfer of digital representations of bank deposits between financial institutions, it remains unclear whether these transactions necessitate the use of Quant’s QNT utility token.
Following the news, QNT hit an intraday high of $373 on September 27, subsequently experiencing a sharp pullback on September 28 to an intraday low of $195.35 before staging a recovery.
What Quant will provide
In June, The Clearing House introduced its On-Chain Money Initiative to enable banks to clear and settle tokenized commercial-bank deposits across different institutions. Unlike publicly issued stablecoins, these tokenized deposits maintain a direct claim on the issuing bank.
The proposed network aims to integrate this activity with traditional fiat payment systems, allowing bank funds to flow seamlessly between on-chain infrastructure and conventional networks. According to The Clearing House, the system is designed to support instant settlement and conditional payments that execute automatically when specific criteria are met.
On September 24, Quant was chosen to handle the connective layer responsible for bridging systems, orchestrating activity, and managing transactions. Additionally, this technology is slated to link the network with RTP and CHIPS, which are two of The Clearing House’s pre-existing payment networks.
Quant’s announcement outlined the same responsibilities and indicated it will deliver Tokenized Deposits-as-a-Service to US institutions utilizing The Clearing House that currently lack their own tokenized deposit infrastructure.
Participating institutions are anticipated to gain access to the network in the first half of 2027. Neither of the September announcements indicated a live rollout, nor did they disclose which banks have opted to subscribe to Quant’s supplementary service.
As a result, this technology selection comes without any published timeline regarding transaction volumes or service revenues.
Under Quant’s general terms, QNT is defined as a utility token that customers can use for various Quant products and services. However, neither The Clearing House nor Quant has stated that participating banks are required to purchase or hold QNT, pay network fees in the token, utilize it as a settlement asset, or burn it.
While banks threw their weight behind the initiative when it was first unveiled in June—prior to Quant’s selection—that backing does not constitute a disclosed commitment to buy QNT or subscribe to Quant’s bank-side offerings.
How a bank payment could reach QNT
According to Quant’s public payment terms, fees may be established during the ordering process, displayed on a subscription dashboard, or outlined in a specific order form. Transaction fees can be billed monthly or annually in advance, accompanied by potential overage invoices.
The agreement permits card payments and invoicing subject to Quant’s approval. Although QNT is typically the exclusive digital asset accepted for entering the Quant ecosystem, this provision still leaves room for fiat transactions.
Furthermore, Quant’s FAQ explicitly notes that platform fees can be settled in US dollars, and subscriptions can be purchased using QNT.
Crucially, the announcements lack any mandate linking a bank’s deposit transfer to the acquisition or lockup of QNT tokens. Consequently, any revenue Quant generates from selling software or services operates independently from direct demand for the utility token.
Historical product descriptions offer additional insight into QNT’s utility elsewhere in the company’s ecosystem. A 2022 overview of the Overledger platform noted that transactions on this interoperability network are powered by QNT, while corporate clients retain fiat payment options.
Overledger serves as Quant’s technology for linking disparate ledgers, though that explanation was published four years prior to the bank-network selection. The announcements made in 2026 do not clarify whether this specific token mechanism applies to the new banking implementation.
Data from The Clearing House’s September release indicates that its existing wire, ACH, check-image, and real-time-payment networks clear and settle upwards of $2 trillion daily.
Developing a reliable estimate for token demand would necessitate a project-specific rule regarding QNT utility, defined fee or conversion mechanics, forecasted or actual transaction volumes on the novel network, and definitive clarity on who will source the tokens.
Future disclosures covering these points could alter market expectations regarding QNT demand. Until then, Quant’s selection cements its participation in a prominent bank infrastructure initiative, even while the connection between that future activity and QNT demand remains undefined.
Frequently Asked Questions
01What is The Clearing House’s On-Chain Money Initiative?
It is a planned network enabling banks to clear and settle tokenized commercial-bank deposits across institutions, connecting on-chain activity with traditional fiat payment systems like RTP and CHIPS.
02What role does Quant play in the new network?
Quant has been chosen to supply the software layer that connects systems, orchestrates activity, manages transactions, and offers Tokenized Deposits-as-a-Service to US institutions.
03Is QNT required to use the new tokenized deposit network?
Neither Quant nor The Clearing House has stated that participating banks must acquire, hold, or spend QNT tokens to use the network or settle transactions.
04When is the network expected to launch?
The network is projected to become available to participating institutions in the first half of 2027.