Bitcoin’s $113,000 case strengthens as US regulators push 9 crypto actions
US regulators have introduced nine crypto actions covering digital asset fundraising, trading, and storage, strengthening the institutional case for Bitcoin as Citi raises its 12-month price forecast to $113,000.

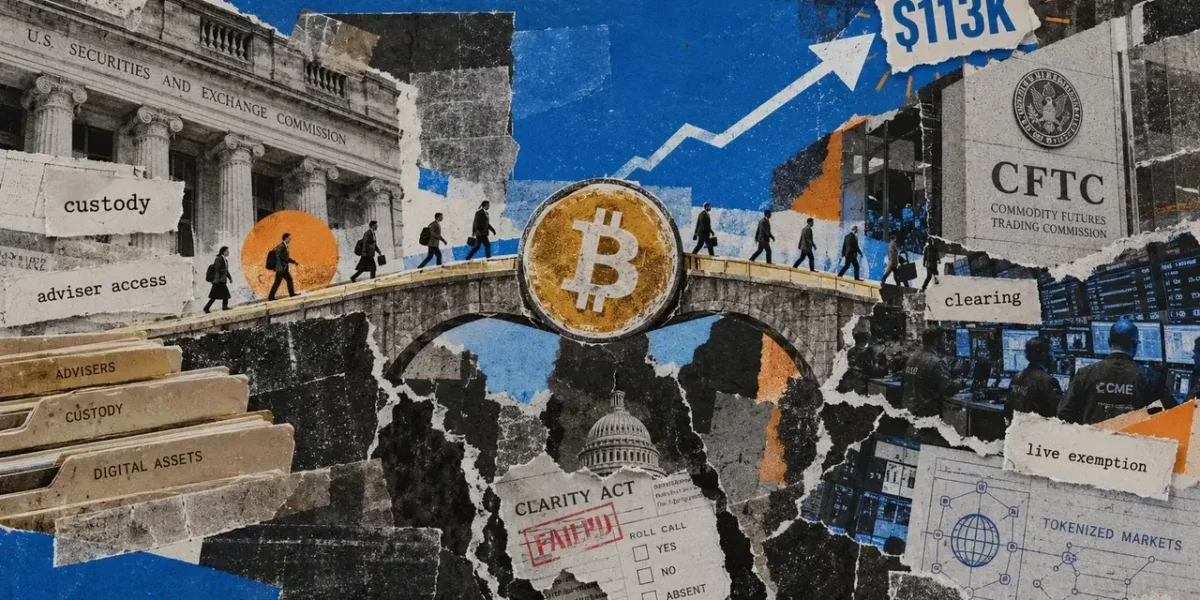
On Oct. 1, the US Securities and Exchange Commission (SEC) introduced a proposed custody framework designed to allow regulated funds and investment advisers to hold crypto assets under specifically tailored rules.
This initiative represents the most recent of nine regulatory agency actions initiated since Aug. 18, which collectively cover the lifecycle of a digital asset from initial fundraising to secure storage. Two of these measures emerged before the Senate voted 49-50 against cloture on the CLARITY Act on Sept. 15 (falling short of the 60 votes required), while seven additional actions have been rolled out since Sept. 17.
Because their current legal standing varies from active exemptions to pre-rule White House reviews, digital asset businesses must evaluate each status carefully to determine what is permissible right now.
Raising money and defining the rules for crypto
Issued on Aug. 18 ahead of the Senate vote, the SEC’s Regulation Crypto Assets proposal seeks to establish an offering framework for specific investment contracts involving digital assets.
The proposal features exemptions covering up to $5 million over a four-year period and $75 million across a 12-month span, alongside a conditional safe harbor from the formal investment-contract classification. Public comments on this proposal remain open until Oct. 20.
Additionally, SEC Corporation Finance staff released a set of FAQs on Sept. 25—and updated them on Sept. 28—addressing token functionality, secondary-market promoters, decentralization, staking receipt tokens, marketing, ongoing network development, and buybacks.
While the SEC characterizes these FAQs as staff perspectives that leave existing statutory laws unchanged, they provide crypto projects with a clear operational roadmap outlining how staff evaluates investment contracts.
Released ahead of the vote on Sept. 1, a separate transfer-agent proposal targets blockchain-based electronic recordkeeping and uncertificated securities. This proposed modernization of the shareholder-record layer underlying tokenized securities remains in the proposal stage.
Trading, routing and collateral
On Sept. 17, the SEC approved its Innovation Exemption. This temporary, five-year conditional exemption allows qualified Tokenized Securities Venues to trade tokenized NMS stocks utilizing permissioned automated market makers and liquidity pools.
Under this live exemption, specific liquidity providers obtain conditional dealer relief, though the measure is strictly temporary and limited to qualifying venues handling tokenized stocks.
Simultaneously, Commodity Futures Trading Commission (CFTC) staff issued a no-action position aimed at passive software providers that link users to registered futures markets and firms. This gives interfaces and wallets a more well-defined pathway into regulated derivatives markets, provided they satisfy specific criteria.
As a staff-level directive, this form of relief carries less legal weight than a formal statute or Commission rule.
On Sept. 24, CFTC staff refreshed its blockchain and crypto FAQs to incorporate customer-funded investments in tokenized versions of authorized investments, alongside the application of blockchain technology to meet specific recordkeeping obligations.
Through these steps, tokenization shifts from isolated trades into the foundational architecture of regulated financial institutions.
Clearing and custody for crypto
On Sept. 28, the CFTC registered Coinbase Clearing LLC as a derivatives clearing organization authorized to clear swaps, fully collateralized futures, and options on futures. This approval brings regulated, crypto-native infrastructure directly into the clearing domain for those designated product categories.
Meanwhile, the SEC’s Oct. 1 custody proposal establishes a custom-built custody structure for registered investment companies, registered investment advisers, and other regulated funds. It allows for self-custody under specific conditions, acknowledges state trust companies as valid custodians for fund and client digital assets, and opens up broader crypto strategy access for regulated funds.
Chairman Paul Atkins characterized the framework as a compliant custody solution where none previously existed. The public comment period lasts for 60 days following publication in the Federal Register, and all proposed provisions remain strictly conditional prior to any final rule.
What works today, and the piece at the White House
Four regulatory measures are fully usable today: the CFTC passive-software relief, the Innovation Exemption, Coinbase Clearing’s registration, and the updated CFTC FAQs for covered registrants.
Conversely, the custody proposal, the transfer-agent proposal, and the Regulation Crypto Assets initiative all require final rules before firms can depend on them, with the SEC FAQs serving as interpretative guides. The final major component is the CFTC’s market framework.
Referred to as “Regulation Crypto Asset Transactions and Regulation Crypto Asset Markets,” this regulatory initiative was sent to the White House for review on Sept. 17. The Office of Information and Regulatory Affairs (OIRA) tracks it as RIN 3038-AF80, a pre-rule designation received that day, keeping its specific details private. It targets the market perimeter—the outermost boundary of the regulatory framework.
Had it passed, the CLARITY Act would have defined regulatory jurisdictions between the CFTC and SEC while creating market-wide guidelines for the secondary trading of digital commodities, leaving that responsibility with Congress for now.
Regulatory bodies retain the authority to issue registrations, interpretations, and exemptions. For example, a joint SEC and CFTC interpretive release issued in March clarified how existing securities laws apply to select digital assets.
While the Innovation Exemption spans five years, Atkins noted on Aug. 18 that overarching legislation remains “indispensable” to ensure rules outlive current regulators.
What the stack means for Bitcoin
Elements such as custody, adviser access, derivatives routing, ETF flows, clearing, and collateral directly impact Bitcoin, while offering regulations apply primarily to token issuers.
Amid Bitcoin trading near $84,600, Citi revised its 12-month price forecast upward from $82,000 to $113,000, pointing to growing ETF inflows alongside gradual increases in brokerage and adviser allocations.
Furthermore, an August survey by CoinShares indicated that digital-asset allocations rose to 1.2%—marking the first increase since the October 2025 market selloff—with regulation cited as the primary concern among invested respondents.
Should the offering, transfer-agent, and custody proposals successfully transition into final rules that align with the CFTC’s market framework, aspects of issuance, trading, collateral, clearing, and custody would operate under a unified regulatory standard.
Such alignment would naturally reinforce the adviser and brokerage allocations highlighted by Citi, corresponding with the higher tiers of Citi’s tokenization projections, which anticipate market values between $2.7 trillion and $8.2 trillion by 2030.
If these regulatory proposals face delays, encounter litigation, or undergo significant rewrites while the CFTC framework remains unpublished, market participants will likely rely on the specific exemptions and no-action directives accessible today.
Under that scenario, the market perimeter would rely entirely on staff positions and agency interpretations. Subsequent court rulings or a future administration could potentially restrict these pathways, pulling potential outcomes toward the lower end of Citi’s Bitcoin forecast range.
Over roughly six weeks, federal agencies have shifted their focus from examining how digital projects raise capital to governing how regulated investors safeguard those assets, leaving the legislative boundary separating the SEC and CFTC unaddressed.
Frequently Asked Questions
01What is the main goal of the SEC’s Oct. 1 custody proposal?
The proposed framework lets registered investment advisers, regulated funds, and investment companies hold crypto assets under customized rules, allowing self-custody under certain circumstances and recognizing state trust companies as legal custodians.
02Are the recent SEC and CFTC crypto actions currently active?
Some measures—such as the Innovation Exemption, CFTC passive-software relief, Coinbase Clearing’s registration, and updated CFTC FAQs—are usable today. Others, such as the custody and offering rules, still require final administrative approval.
03How does regulation affect Bitcoin’s price outlook?
Analysts like Citi suggest that clear regulatory alignment across custody, trading, and clearing can drive institutional adviser allocations and ETF inflows, supporting long-term price forecasts reaching up to $113,000.