यूके के 2027 के क्रिप्टो नियम फर्मों को यील्ड के लिए उधार दिए गए बिटकॉइन से ट्रस्ट सुरक्षा हटाने की अनुमति देते हैं
FCA आवेदन अब खुले होने के कारण, अपेक्षित अक्टूबर 2027 की व्यवस्था दायरे में आने वाले खुदरा उधार संपार्श्विक के लिए सुरक्षा उपायों को बनाए रखेगी, साथ ही ऋण देने वाले ट्रस्ट की छूट की भी अनुमति देगी। द पोस्ट UK’s 2027 crypto rules let firms remove trust protection from Bitcoin lent for yield appeared first on CryptoSlate.

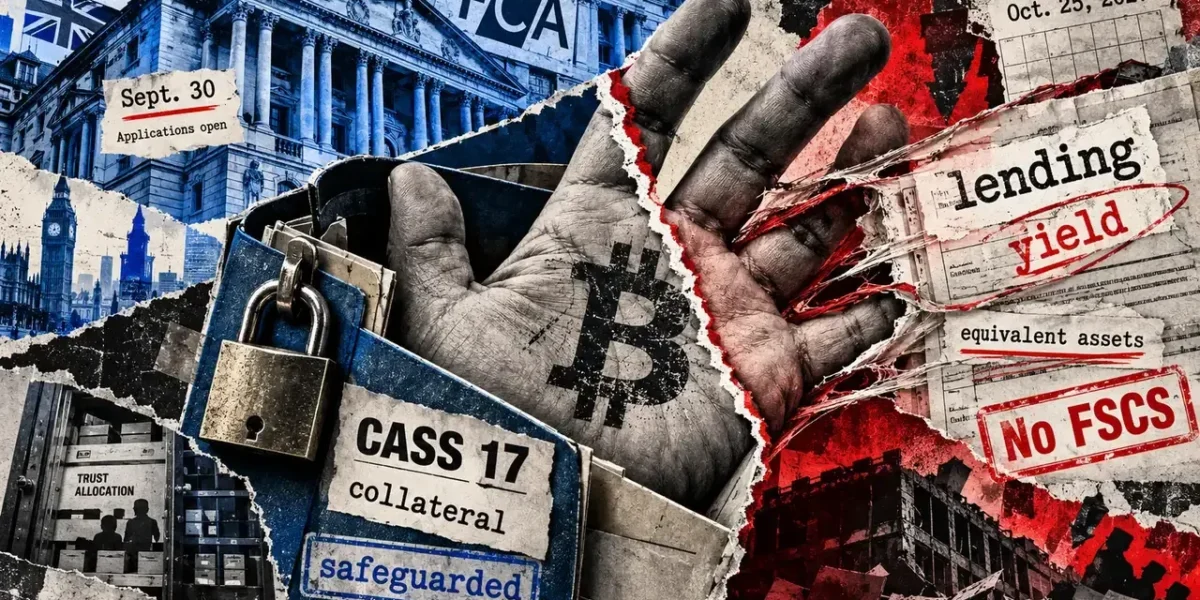
UK crypto businesses can now request authorization as of Sept. 30, taking Bitcoin holders a step closer to a regulatory framework that will handle coins pledged as qualifying borrowing collateral differently from those transferred into yield-bearing lending schemes. This distinction is crucial if a platform collapses, as safeguarded assets versus a contractual guarantee to hand back equivalent coins provide clients with distinct paths for recovery.
The Financial Conduct Authority currently permits firms to apply for authorization or adjust their permissions via its Connect system. Nonetheless, the safeguards outlined in the guidelines finalized on June 30 are still pending, with the updated regime anticipated to launch on Oct. 25, 2027. Submitting an application today neither grants authorization nor enforces those protections immediately.
The primary divergence involves how platforms are permitted to handle customer funds. Under upcoming policies, standard custody generally mandates a safeguarding trust under CASS 17—the crypto custody section of the FCA’s Client Assets Sourcebook. Retail collateral backing a regulated crypto borrowing arrangement must stay protected, subject to a strict debt-discharge carve-out. Conversely, qualifying lending operations can utilize an exemption from the trust obligation while the lending activity persists. Asset protection applies specifically to qualifying cryptoasset borrowing, which is a strictly defined service and does not automatically cover every cash loan marketed as being backed by Bitcoin.
The different legal frameworks governing how customers request their coins back become vital when assets are missing. Recovery ultimately relies on whether the failed enterprise holds sufficient assets for repayment, and these newly regulated crypto activities will continue to lack coverage from the Financial Services Compensation Scheme.
Pledged coins must remain safeguarded
Under the upcoming regulatory structure, the FCA’s retail collateral mandate requires any company offering qualifying cryptoasset borrowing to secure appropriate protection for relevant crypto collateral. Firms may safeguard the assets directly if they hold the proper permissions, or they can appoint an adequately authorized custodian provided they hold permissions to arrange such safeguarding.
When Bitcoin serves as collateral in these arrangements, the company cannot simply acquire full ownership to deploy the tokens elsewhere. The regulation prevents both the enterprise and any third party from assuming full ownership unless the retail client grants explicit prior consent to transfer ownership specifically to settle debt generated by that borrowing activity.
The corresponding debt-discharge provision introduces another prerequisite. A binding, written agreement must grant the enterprise the legal right to take ownership to satisfy a debt, and the business must actively execute that right according to the contract terms. Until the firm executes that agreed-upon right, simply signing the paperwork leaves the coins bound by safeguarding requirements.
The practical result is that pledging coins does not instantly convert them into the platform’s freely accessible inventory. The duty to safeguard persists unless an approved alteration in their handling takes place. Consequently, borrowing against tokens must be kept separate from surrendering them to a yield-driven lending program.
For any borrower evaluating financial products, legal classification is therefore critical. These regulations govern qualifying cryptoasset borrowing, a clearly defined service whose legal treatment depends on the underlying substance of the arrangement. FCA perimeter guidelines dictate that the legal reality of an agreement alongside participant roles defines its classification. The retail collateral mandate cannot be broadly applied to every cash loan secured by Bitcoin.
Retail and wholesale boundaries also diverge. The main lending and borrowing chapter generally applies to retail clients who are not classed as overseas retail clients, whereas specific recordkeeping and transfer rules have a wider reach covering clients who are not overseas participants.
Lending can change the customer’s claim
Qualifying cryptoasset lending moves digital assets in the opposite direction. According to FCA definitions, a person transfers cryptoassets to or via another party under an obligation or right to reclaim identical or equivalent assets, typically in exchange for yield.
This return right differs fundamentally from an instruction to hold coins in safe custody. Pursuant to CASS 17.3.4, a business offering qualifying lending services can be excused from acting as a trustee for those specific assets throughout the duration of the service. If the business already holds them within a safeguarding trust, the rule permits it to cease treating them as client cryptoassets while the exemption remains active.
The exemption expires when the lending service terminates, including instances where the client exercises a contractual right to end it. Actual retrieval still hinges on coin availability, agreed return timelines, and access constraints. Concluding the service consequently leaves open questions regarding when the customer will manage to recover the owed assets.
Crucially, the lending exemption is unavailable for qualifying borrowing collateral. A distinct exemption covering other services that require ownership transfers also does not apply to this collateral. The rulebook thus blocks these loopholes from weakening the safeguards placed on collateral.
For clients whose coins have been shifted into lending activities outside the mandatory trust, expecting a CASS 17 trust claim is incorrect. Recovery may instead rely upon contractual return rights alongside standard insolvency procedures. The contract terms and overall service structure define the exact nature of the claim; the exemption does not place every lending customer into an identical creditor tier.
The FCA’s upcoming disclosure guidelines integrate this distinction directly into customer communications. Companies are required to deliver details regarding transfers, asset returns, account access, yield generation, and associated risks. Regulatory guidance also emphasizes explaining the consequences of ownership transfers, including scenarios where the company or an associated party becomes insolvent.
For investors earning yield, reviewing the underlying agreement is essential to comprehending the claim that corresponds to any balance shown on a software application. The contract must clarify whether the coins stay protected, whether ownership changes hands, and what must be handed back once the service concludes.
Custody recovery still depends on assets and costs
For protected custody operations, CASS 17 generally obligates enterprises to safeguard cryptoassets as trustees under formalized legal agreements. The FCA notes that these trusts aim to protect client rights against competing claims, particularly if the custodian faces insolvency.
Regulations demand that firms establish private trusts through appropriate legal channels. The safeguarding duty relies upon those formal arrangements actually being created, rather than stemming from any statutory trust arising automatically out of the rules. Such structures and their execution must continuously satisfy designated legal and safeguarding requirements.
Asset boundaries are likewise significant. CASS 17 application rules focus on regulated activities executed from a UK establishment, barring specific exceptions. The FCA’s final-policy summary indicates that custody of relevant designated investment cryptoassets will initially adhere to separate CASS 6 guidelines. Consequently, varying assets and operational frameworks can fall under entirely different custody mandates.
Detailed records help determine what properly belongs inside the trust. Upcoming reconciliation rules mandate calculations of what a business must maintain for every individual client, trust, and asset category at least once per business day. While this aids in recognizing entitlements, identifying a right to assets is distinct from possessing the physical assets needed to fulfill it.
Trust documentation must outline how deficits are distributed if multiple clients share a single trust. Terms must also clarify whether client funds can be used to cover distribution costs following trustee default and explain the mechanics of such deductions. The FCA generally expects that any shortfall within a specific asset class inside a trust should be shared proportionately amongst impacted clients.
These stipulations ground recovery limitations in reality. While a trust strengthens the legal footing of an asset claim, it cannot guarantee complete reimbursement following losses or administrative costs.
Staking must also be treated separately from lending. FCA collateral guidance dictates that staking eligible collateral should remain permissible only if firms comply with staking regulations, refrain from transferring full ownership, and maintain trust safeguarding. This conditional treatment does not equate to establishing a lending exemption for borrowing collateral.
Authorization will not add FSCS insurance
The boundary regarding compensation remains unaffected by the transition to formal authorization. Within the future Handbook glossary, the FCA incorporates the new crypto activities into the definition of designated investment business for broad Handbook purposes, while explicitly excluding them when that identical term appears within compensation regulations.
These exclusions encompass crypto safeguarding, arranging safeguarding, running trading platforms, executing and arranging deals involving qualifying cryptoassets, issuing stablecoins, and organizing staking. Combined with protected-claim guidelines, this implies that official authorization for these fresh activities does not extend FSCS investment compensation protections.
While a firm might engage in other lines of business carrying different compensation eligibility, its approval to handle an uncovered crypto service cannot magically transform that offering into a protected investment claim.
The Financial Ombudsman Service represents an alternative avenue. Jurisdictional rules under DISP can accommodate qualifying grievances regarding regulated activities, provided relevant conditions are met. A valid complaint focuses on corporate behavior and misconduct. Payouts for any resulting award still depend on specific conditions, whereas FSCS eligibility remains entirely separate.
Prior reports outlined the timeline for authorizations alongside the perimeters established for stablecoins and lending.
Access for offshore platforms forms another piece of the broader regulatory landscape. For everyday users, the critical question centers on how a chosen service treats digital assets after the operating platform secures its mandatory permissions.
In its June policy summary, the FCA indicated plans to consult later in 2026 regarding the management of cryptoasset firm failures, which will cover distribution protocols for distressed custodians and stablecoin issuers. The final design of these failure and distribution frameworks will profoundly influence practical outcomes for customers.
As application windows open, the key distinction for Bitcoin holders lies between accessing a regulated service versus the specific rights tied to their coins within it. Custody arrangements, qualifying borrowing collateral, and yield-focused lending can trigger entirely different asset claims. The framework arriving in October 2027 will render these distinctions far more explicit, though customer recovery will still rest heavily upon the underlying arrangement, available assets, and applicable insolvency procedures.
अक्सर पूछे जाने वाले प्रश्न
- When do the new UK crypto rules take full effect? The new regime is expected to begin on Oct. 25, 2027, though firms can apply for authorization starting Sept. 30.
- Does authorization include FSCS protection for crypto assets? No. Authorization for these new crypto activities does not add Financial Services Compensation Scheme (FSCS) investment protection.
- What is the difference between crypto borrowing collateral and crypto lending for yield? Qualifying borrowing collateral must generally remain safeguarded under strict trust requirements, whereas qualifying lending services can use an exemption from the trust requirement while the lending continues.
- Are staking and lending treated the same way under the rules? No. Staking eligible collateral requires compliance with staking rules, no transfer of full ownership, and continued trust safeguarding, whereas lending involves different exemptions and risks.