Why Strategy’s STRC calculator shows $210 for a share it can redeem at $101
Strategy's STRC credit calculator generated an illustrative price of $210.90 while market prices hovered near $99.50 and redemption options stood at $101. This discrepancy highlights formula limitations, including the omission of issuer call option valuations.

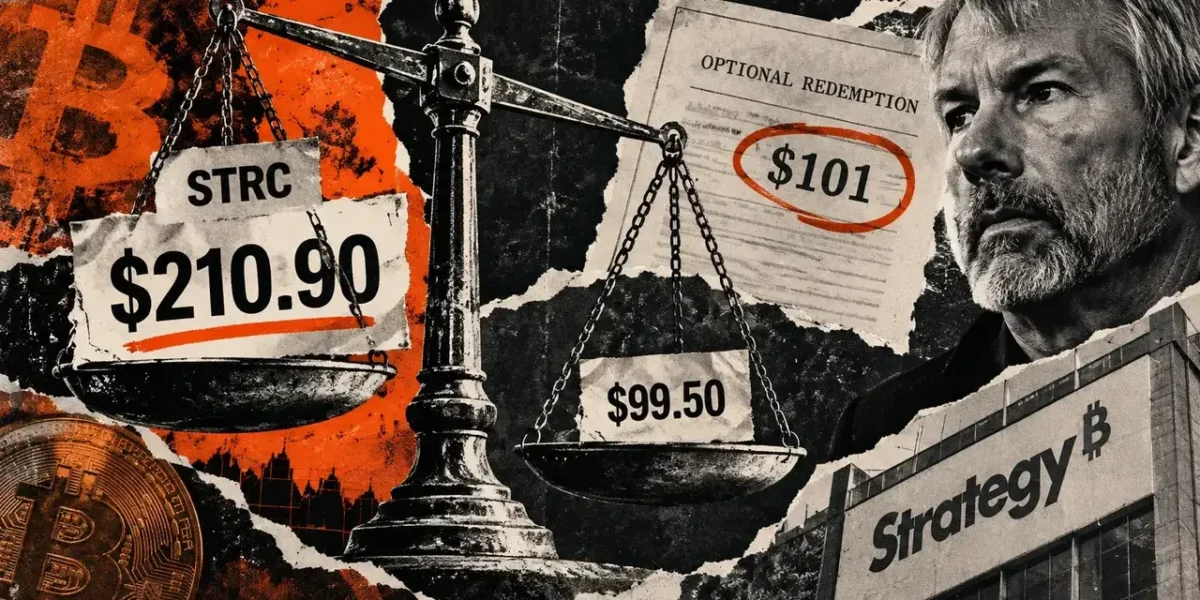
Strategy’s Bitcoin credit calculator generated an illustrative STRC price of $210.90 on Oct. 2, while showing a market-price input of $99.50 for the perpetual preferred stock. Meanwhile, the issuer maintains the option to redeem shares at $101, or a higher amount of its choosing, plus any applicable unpaid dividends.
That discrepancy highlights the limitations of the calculation. The published formula keeps the current dividend constant and substitutes a modeled Bitcoin spread for the market’s credit spread. It features no explicit valuation of the issuer’s call option nor outlines a trajectory for future dividend resets. Strategy’s pricing dashboard separately highlights those characteristics and cautions that the call can cause the Derived Price to diverge significantly from realizable market prices.
For purchasers, the calculation offers a perspective on the security under specific assumptions. It does not prove that STRC is worth more than twice its visible market price, nor does it guarantee that a holder can obtain either the model output or the redemption value on demand.
How the calculator reaches $210.90
At roughly 08:18 UTC on Oct. 2, the dashboard applied a Bitcoin price input of $86,593, a projected annual return of 10%, and a volatility rate of 40%. Its STRC row displayed a 12.06% effective yield, a 5.23% risk-free yield, and 46 basis points of BTC Credit, which is Strategy’s modeled credit spread.
The published pricing formula divides the annual dividend by the total of the risk-free yield and BTC Credit. Applying a $12 annual dividend alongside the displayed inputs results in:
$12 ÷ (5.23% + 0.46%) ≈ $210.90.
This arithmetic yields the rounded figure. The row’s market spread—representing the extra yield above the risk-free rate based on the shown market price—was 684 basis points. BTC Credit serves as the model’s estimation of that credit spread. Substituting 46 basis points for the substantially larger market spread reduces the formula’s discount rate and drives its output upward. Rounded yield inputs do not necessarily have to mirror the displayed market spread precisely.
This formula illustrates the underlying economic mechanism. When other inputs remain unchanged, a higher dividend boosts the numerator, whereas a smaller modeled spread reduces the denominator. Maintaining a high current dividend alongside a much smaller spread can generate a high illustrative price without altering the actual rights held by investors.
Strategy explicitly states that the output functions neither as a fair-value determination nor as a price target. Its assumptions incorporate full scheduled payments along with a simplified approach to Bitcoin coverage and claims. The dashboard also warns that displayed market prices can become stale and do not represent executable quotes. These figures represent a dated snapshot, as Bitcoin-linked model inputs are subject to change following observation.
Consequently, the output cannot pinpoint why the market price diverges from the calculation. Issuer options, payment risk, prevailing trading conditions, and the model’s assumptions all influence the comparison, meaning the entire gap cannot be attributed solely to the call right.
Under STRC’s amended certificate of designations, Strategy retains the right to pursue an optional redemption at $101 per share or a higher amount specified through an announcement. Applicable accumulated unpaid dividends and compounding are factored in, along with adjustments for declared dividends that are payable separately to record holders.
Any partial optional redemption must leave a minimum of $250 million in stated amount outstanding and uncalled at the time notice is issued. The redemption date follows the notice by a window ranging from three business days to 60 calendar days. These provisions dictate issuer actions rather than granting ordinary holders the right to cash out.
Should Strategy exercise this option, the holder receives the contractual redemption payment rather than keeping ownership of the dividend-paying share. This factor is critical when evaluating a calculation that capitalizes the current dividend without explicitly pricing a call.
Nevertheless, the $101 figure neither guarantees a redemption nor establishes an absolute ceiling for the secondary-market price. Strategy may choose not to execute a call, and the certificate allows for a higher announced amount. Furthermore, a buyer cannot presume the company will initiate a redemption simply because STRC trades below that threshold.
These three prices reflect distinct concepts: $99.50 serves as the dashboard’s market input, $210.90 acts as an assumption-driven output, and $101 plus applicable dividends constitutes a potential issuer-selected redemption payment. Each is subject to its own unique conditions.
The numerator is also flexible. STRC’s current rate does not guarantee the same level of cash income indefinitely.
For every monthly reference period, standard rate reductions are limited by a 25-basis-point allowance alongside designated declines in one-month term SOFR, a SOFR floor, and specific conditions regarding prior accumulated dividends. Those dividends must be disbursed or fully declared with adequate consideration set aside. While these restrictions constrain discretion, they do not eliminate it entirely.
STRC dividends accumulate on a cumulative basis. Actual cash distribution still requires board declaration and the presence of legally available funds. An accumulated entitlement and the cash collected on a specific date represent separate considerations for anyone depending on that income.
The payment schedule has already shifted away from the monthly timeline outlined in the July 2025 offering announcement. The amended certificate, which took effect on June 30, 2026, instituted twice-monthly payments while keeping monthly reference periods for rate resets.
Strategy’s Oct. 1 filing notes that its Sept. 30 action preserved the 12% annual rate for periods commencing Oct. 16 and declared a $0.50 payout for the semi-monthly period concluding on Oct. 31.
The daily-dividend proposal is pending an Oct. 28 shareholder vote. If approved and implemented on schedule, with dividends formally declared by the board, the targeted initial daily record date will be Nov. 1, followed by the first payment on Nov. 2. Subsequent payments would occur on the business day following each record date.
Transitioning to more frequent payments would alter the timing of cash inflows, but it would not establish a daily redemption right, lock in the dividend rate, or ensure principal stability.
Bitcoin coverage does not replace dollar capacity
Strategy’s Bitcoin reserves and its cash-payment capabilities address entirely different questions. Bitcoin coverage pertains to assets evaluated against claims under the model’s baseline assumptions. Conversely, dividends payable in USD require actual dollar liquidity when payments fall due.
Within its Sept. 28 reserve update, Strategy disclosed a $5.02 billion USD Reserve alongside a separate $1.00 billion USD Cash balance as of Sept. 27. The reserve is allocated to support preferred dividends and debt interest, whereas USD Cash is maintained for broader treasury and capital-allocation objectives.
During the week of Sept. 21–27, the firm utilized $22.1 million from the reserve for preferred dividends and allocated $48.1 million of USD Cash to help finance STRC repurchases. These figures reflect historical balances and expenditures rather than a guarantee of future payment coverage. The wider cash pool should not be viewed as interchangeable with the designated reserve.
Claim priority is another crucial consideration. Debt obligations and STRF rank ahead of STRC, whereas STRK, STRE, and STRD represent junior preferred claims. Bitcoin is not pledged directly to STRC holders, meaning additional senior claims or alternative liabilities can impact the assets accessible to them.
Michael Saylor’s Sept. 29 commentary regarding digital credit outlines Bitcoin capital and dollar liquidity as distinct components of the architecture. He frames reserve management, financing, and discretionary buybacks as tactical tools, while clarifying that repurchases do not guarantee a price floor. These represent management decisions and goals rather than assurances built directly into the calculator.
Earlier CryptoSlate reporting analyzed third-party dividend-durability modeling and Strategy’s allocation toward buybacks. The issuer’s proprietary pricing formula introduces a more specific inquiry: what insights can purchasers actually derive by replacing a single spread while leaving other inputs unchanged?
The answer is constrained by the parameters of the formula itself. Modifications to the declared rate alter the income stream being capitalized; a call option dictates how long an investor retains that income; and reserve management choices alongside senior claims dictate payment capacity. As of the Oct. 2 snapshot, the calculator’s substantial divergence from the displayed market price failed to resolve any of those contractual and payment inquiries.
Frequently Asked Questions
01What is the purpose of Strategy’s STRC calculator?
The calculator provides an illustrative valuation of STRC by replacing the market credit spread with a modeled Bitcoin spread while holding the current dividend constant.
02Does the calculator output represent a guaranteed price for STRC?
No. Strategy explicitly states that the output is not a fair-value determination, a price target, or an executable quote, and that it does not account for the issuer’s call option.
03What is the redemption price for STRC shares?
Strategy retains the option to redeem shares at $101—or a higher announced amount—plus any applicable accumulated unpaid dividends, subject to specific notice periods and conditions.
04Are STRC dividends guaranteed indefinitely?
No. While dividends accumulate cumulatively, cash payments depend on board declarations, legally available funds, and adherence to specific rate-reduction constraints.