Hedge funds built a $1.2 trillion Treasury trade on money they have to keep borrowing
Hedge funds have built a massive $1.2 trillion Treasury cash-futures basis trade utilizing heavy leverage through short-term repo borrowing, creating vulnerabilities when financing costs rise or liquidity tightens.

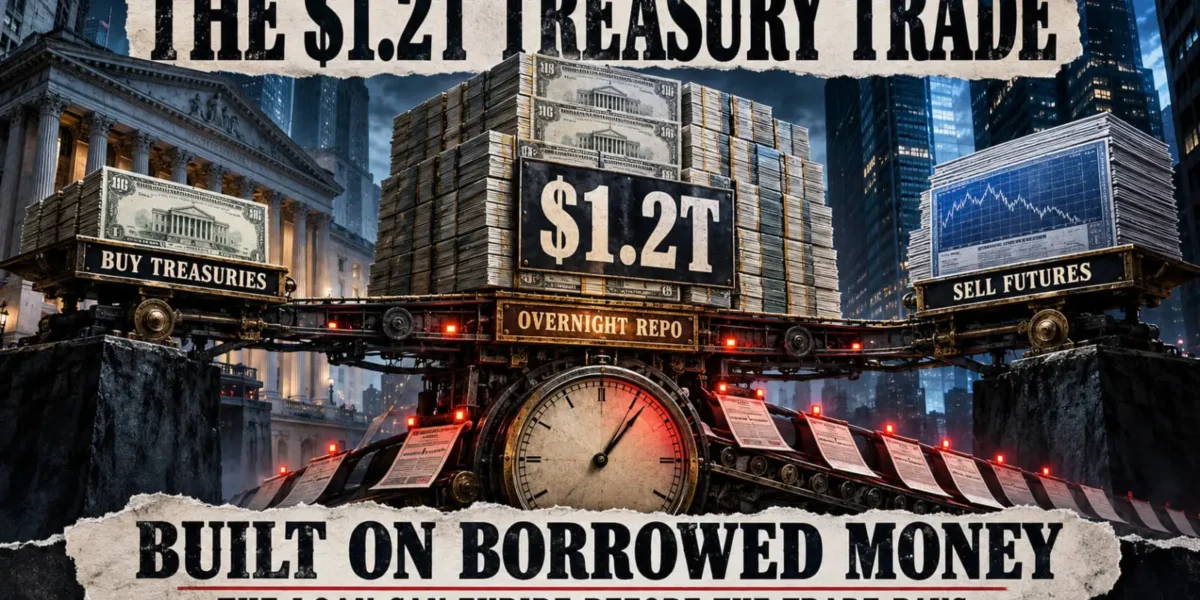
Organizations can hold massive amounts of U.S. government debt without having to wager on rising bond prices. By purchasing Treasury securities and simultaneously selling futures against them, hedge funds capture narrow pricing discrepancies, utilizing heavy leverage through borrowing to make the ultimate return worthwhile.
The government benefits by gaining another buyer whose participation endures for as long as the trade remains profitable.
The complication arises because the underlying loan can expire tomorrow, whereas the trade itself requires a longer timeframe to mature. The federal government’s creditworthiness and ability to repay its obligations do not resolve a fund’s immediate need to satisfy its creditor.
This mechanism is known as the Treasury cash-futures basis trade, and the capital involved extends far beyond standard bond desks. According to reports from September 24, Morgan Stanley estimated that these positions had dropped by 20% this year to roughly $1.2 trillion.
At the time, the bank found no signs of widespread basis-related market distress, indicating that a smaller volume does not automatically signal an impending market blowup.
Hedge funds love small profits when it’s someone else’s money
An investor can purchase a Treasury security outright or trade a futures contract that locks in terms today for settlement at a later date. Because the contract defines which specific securities qualify for delivery, it connects their prices without making the instruments identical.
When futures grow sufficiently expensive compared to an eligible bond, a fund will purchase the bond and sell the futures. Investors seeking bond-market exposure via contracts take the opposite side of the transaction, leaving the hedge fund to hold the actual underlying securities.
Executing the short futures sale acts as the hedge: if bond prices drop, the short position generates gains that can offset a large portion of the bond’s decline. The fund’s objective is to capture the pricing spread as the contract nears delivery while minimizing its exposure to broader market movements.
To fund the bond acquisition, the fund utilizes the repo market, short for repurchase agreement. In this arrangement, the fund sells the security for cash and agrees to repurchase it later at a slightly higher price—a structure that functions economically as a loan secured by the bond.
Because these are overnight repo transactions, the fund must continually renew or replace its financing to maintain the position.
Consider a hypothetical $100 million position generating a net annual return of 0.2% after accounting for financing and trading expenses. That equals $200,000, which translates to a lucrative 4% return if the fund has deployed only $5 million of its own capital.
However, if the borrowing costs associated with the remaining $95 million rise by 0.2% over the course of the year, the additional expense totals $190,000. Nearly the entire projected profit is absorbed by the lender, even though the government has not defaulted on anything.
The Office of Financial Research factors in the cost of futures margins as well as the seller’s options regarding which eligible bond to deliver and when. Properly calculating returns requires placing a value on these delivery rights while accounting for both financing and margin expenses.
If those calculations lose their appeal, a fund can simply choose not to roll over positions as they mature. Professional investors do not require a full-blown crisis to redirect their capital toward better opportunities.
Being right doesn’t pay today’s bill
Even if the hedge functions as intended, a fund may lack the liquidity to make the cash payments required to keep the position open.
Imagine a scenario where the bond increases in value while the short futures position suffers an equivalent loss. The futures account may demand a cash settlement for that loss, known as variation margin, whereas the gains on the bond remain locked up inside the security.
The fund must either extract cash from that asset or source funds elsewhere prior to the payment deadline.
Cryptocurrency traders experiencing unrealized gains on one exchange while facing imminent liquidation on another will find this dilemma familiar: capital stranded in the wrong account cannot satisfy a margin call, and explaining the mechanics of a hedge will not grant a deadline extension.
Repo lenders can also demand increased collateral. If a lender provides $98 against $100 worth of bonds, the fund contributes the remaining $2, representing a 2% haircut. Should that haircut jump to 4%, the fund must supply twice as much of its own capital against the exact same collateral, independent of any futures margin requirements.
When numerous funds are forced to unwind positions simultaneously, they sell bonds to pay off loans and buy futures to cover short positions. Such synchronized trading can depress bond prices relative to futures, penalizing other funds holding identical positions and driving up their exit costs.
This type of forced liquidation differs from letting trades naturally expire without renewal, though both actions reduce total outstanding positions. Simply observing a contraction in reported figures does not reveal which of the two dynamics is occurring.
Federal Reserve researchers estimated $830 billion worth of basis positions for September 2025 in a publication released this June. Because that figure and Morgan Stanley’s more recent estimate utilize different methodologies, treating them as sequential readings creates a comparison that the underlying data cannot support.
Furthermore, total hedge-fund Treasury holdings encompass alternative strategies, as do their short futures positions.
Someone still has to own the Treasury bonds
A reduction in trades reliant on short-term overnight financing can render the market less fragile, provided that subsequent buyers bring stable capital capable of weathering a turbulent week. Investors acquiring assets with fully committed capital are not subjected to daily refinancing negotiations with repo lenders.
These buyers may demand more attractive pricing because they acquire bonds primarily for their income potential. Cheaper bonds deliver higher yields, enticing replacement demand while potentially increasing the cost of new government borrowing.
While primary dealers can hold bonds while searching for end buyers, their balance-sheet capacity is limited and expensive. Consequently, an orderly market transition may result in Washington paying higher yields without causing a breakdown in market function.
Elevated repo rates or stricter haircuts become far more alarming if funds are forced into selling within a market lacking willing buyers. Financing terms and prevailing sell-side prices offer a much clearer picture of market stress than aggregate position totals alone.
This same restraint applies to Bitcoin, as the broader balance sheets of hedge funds demonstrate why any single strategy cannot encapsulate all activities undertaken by these firms.
Connecting distress in the Treasury market to crypto demands concrete proof that the institutions involved are liquidating digital assets or withdrawing financing, rather than assuming every corporate liquidity need concludes with a Bitcoin sale.
Ultimately, borrowed leverage is what induces these funds to hold government bonds for returns that would otherwise be far too meager to pursue.
When those economic calculations break down, replacing leveraged funds can diminish the market’s reliance on overnight loans, though the incoming buyer may require a higher yield to take the debt off their hands.
Frequently Asked Questions
01What is the Treasury cash-futures basis trade?
It is a strategy where hedge funds buy U.S. Treasury securities and simultaneously sell futures contracts against them to capture a small pricing gap. Because the profit margins are thin, funds borrow heavily—often via overnight repo agreements—to scale up the trade.
02Why is leverage a risk in this trade?
While the trade itself may be hedged against overall bond price movements, the financing used to support it relies on short-term loans. If borrowing costs spike, margin requirements increase, or lenders demand higher haircuts, funds may be forced to unwind positions suddenly.
03How does this relate to broader market stability?
A contraction in basis trade positions can reduce the financial system’s reliance on fragile overnight repo loans, but it may also require ultimate buyers to demand higher yields to absorb the government debt, potentially raising borrowing costs for Washington.