Aave and Pendle may have found a way to keep yield capital from ever leaving DeFi
Aave prepares for a $67 million collateral rollover as its Pendle fixed-yield trade approaches maturity, testing a continuous decentralized finance yield cycle.

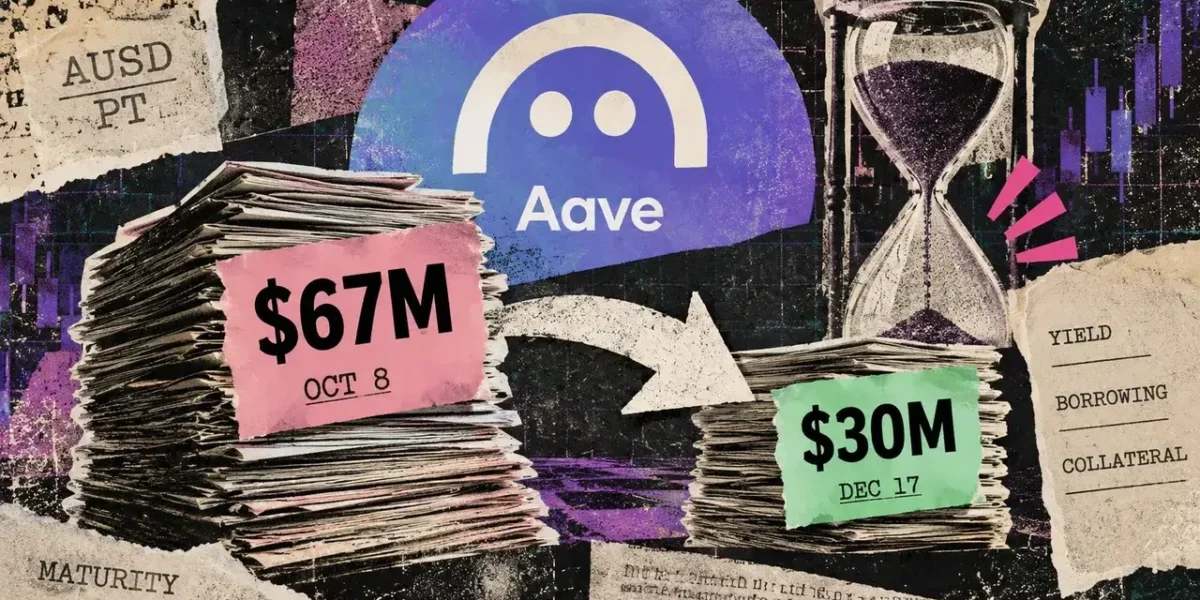
Aave is preparing for a $67 million collateral rollover as one of its fastest-growing fixed-yield trades approaches its maturity date.
Data from risk adviser LlamaRisk shows that approximately 67.4 million PT-AUSD-8OCT2026 tokens were deposited as collateral on Aave V3’s Monad market as of Oct. 2. These Pendle principal tokens are set to mature on Oct. 8, at which point each token becomes redeemable for one AUSD, bringing its fixed-yield appreciation to a close.
Preparations for a replacement are already underway. Pendle launched a Dec. 17 AUSD principal-token market last month, and TokenLogic has put forward a proposal to list it on Aave. This would allow borrowers to transition into the subsequent maturity without sacrificing the collateral utility that drove the expansion of the October market.
This timing aligns with a surge in demand for AUSD credit on Monad. TokenLogic reported that active AUSD loans on Aave climbed 113% over a 15-day period to $8.7 million from $4.1 million by Oct. 3, while user deposits more than doubled to reach $11.2 million.
This dynamic establishes an ongoing cycle between Aave’s lending platform and Pendle’s fixed-yield markets. Investors have the ability to lock in returns via PT-AUSD, leverage that position as collateral to borrow stablecoins, and subsequently shift into a later-dated principal token once the original asset matures.
DeFi researcher Andree characterized the interaction between the two protocols by stating, “Fixed yield becomes collateral. Collateral creates credit. Then the next maturity keeps the cycle moving.”
The upcoming Oct. 8 expiration serves as the initial large-scale evaluation of whether this mechanism can successfully operate across successive maturities.
A $20 million market grew past $67 million
The October principal token market began with a much smaller capacity than it ultimately achieved.
Avenue initially introduced the collateral market with a supply cap of 20 million tokens. Users exhausted this limit by late August, prompting LlamaRisk to suggest an increase to 40 million. After that threshold was also quickly utilized, the risk adviser recommended raising the limit further to 80 million.
By Oct. 2, the supply of PT reached 67.4 million.
These rapid adjustments indicate that the proposed size for the December market should not be viewed as a definitive limit. TokenLogic suggested an initial cap of 20 million for PT-AUSD-17DEC2026, while LlamaRisk recommended starting at 30 million.
Although that initial figure is less than half the volume held in the expiring market, the precedent set in October demonstrates that Aave can scale its capacity if market demand, available liquidity, and borrower safety metrics support it.
LlamaRisk explicitly identified the December principal token as the designated rollover option for the October position, noting that as much as 67.4 million of Aave collateral could potentially migrate over.
Furthermore, the October market data indicates that much of the deposited PT was actively utilized rather than left dormant. An assessment by LlamaRisk on Aug. 31 revealed that the 18 largest suppliers all maintained active debt, primarily denominated in USDC, along with additional borrowings in GHO, USDe, and USDT0.
At that time, their median health factor sat at 1.02. This tight margin stems from a configuration where both the collateral and the corresponding debt are pegged to the dollar, allowing borrowers to maintain high loan-to-value ratios with reduced directional price risk compared to crypto-backed leverage strategies.
While maturity does not automatically trigger liquidations—borrowers can redeem PT for AUSD following expiration, settle their loans, or provide alternative collateral—a user carrying debt against the October principal token cannot automatically withdraw their collateral unless the position remains adequately funded.
Executing a direct rollover into the December PT provides an alternative pathway for maintaining the existing borrowing position.
The next market still has to scale
A more immediate bottleneck may arise from the scale of the replacement market itself.
According to LlamaRisk, the December Pendle pool held only $1.61 million in liquidity, 904,717 PT in circulation, and $44,000 in trading volume since its deployment as of Oct. 2.
These metrics are modest when compared to the tens of millions of dollars tied up in the October position.
Because Pendle users can mint additional principal tokens by splitting yield-bearing AUSD holdings into principal and yield components, existing pool liquidity does not impose an absolute restriction on the total collateral that can be generated. Nevertheless, large-scale migration can still influence execution pricing and the fixed returns available to buyers.
Current economic conditions are also tighter than they were at the launch of the October market.
LlamaRisk calculated the implied yield of the December PT at 5.64% on Oct. 2, with a temporary one-percentage-point campaign incentive boosting the effective rate to 6.64%.
At the time of the snapshot, this exceeded borrowing rates of 4.28% for mUSD, 4.64% for GHO, 5.10% for USDT0, and 6.09% for USDC, leaving room for positive carry prior to accounting for transaction fees and price impact. However, it remained below the 6.82% borrowing rate associated with USDe.
These financial spreads are subject to rapid shifts. Aave borrowing rates fluctuate based on utilization levels, whereas PT yields adjust according to trader buying and selling activity. Additionally, the incentive enhancing the December returns is temporary in nature.
The expansion of AUSD borrowing introduces another layer to the rollout. The $8.7 million in active AUSD loans is distinct from the stablecoin debt secured directly against PT-AUSD, yet both highlight rising demand for AUSD-denominated credit on Monad.
Sustaining the utility of the principal token across successive maturities could help retain fixed-yield capital within Aave as each Pendle market concludes.
The coming days will determine how much of the October collateral successfully navigates this transition.
Should the December PT begin reaching its initial cap as quickly as its predecessor, Aave’s risk managers may face renewed pressure to increase limits. Their readiness to do so will rely on Pendle’s liquidity conditions, borrower health metrics, and whether the new market builds sufficient depth to back tens of millions of dollars in collateral.
For borrowers, decisions are more pressing: they must choose between settling debts at maturity, substituting collateral, or securing allocation in the December market while the yield spread remains favorable.
Frequently Asked Questions
01What happens when a Pendle principal token matures on Aave?
When a principal token matures, each token becomes redeemable for its underlying asset (such as AUSD), and its fixed-yield appreciation concludes. Borrowers with active loans backed by these tokens must ensure their positions remain properly covered by redeeming the tokens, repaying loans, or supplying alternative collateral.
02Can borrowers roll over their expiring collateral into a new market?
Yes. Protocols like Pendle and Aave are designed to allow users to transition their positions into later-dated maturities—such as shifting from the October market to the December market—without sacrificing their overall collateral utility or borrowing positions.
03What is the risk of using stablecoins as both collateral and debt?
Using dollar-denominated collateral to borrow dollar-denominated stablecoins minimizes directional price risk compared to volatile crypto assets. However, borrowers must monitor their health factors closely, as borrowing rates and yield spreads can shift based on market utilization and variable interest rates.