Inflation target of 2% may not stop the next Fed rate freeze
The Federal Reserve may halt interest-rate increases before inflation hits the 2% target if policymakers see clear evidence the economy is moving toward that goal independently, driven by moderating price growth, easing spending, or rising unemployment.

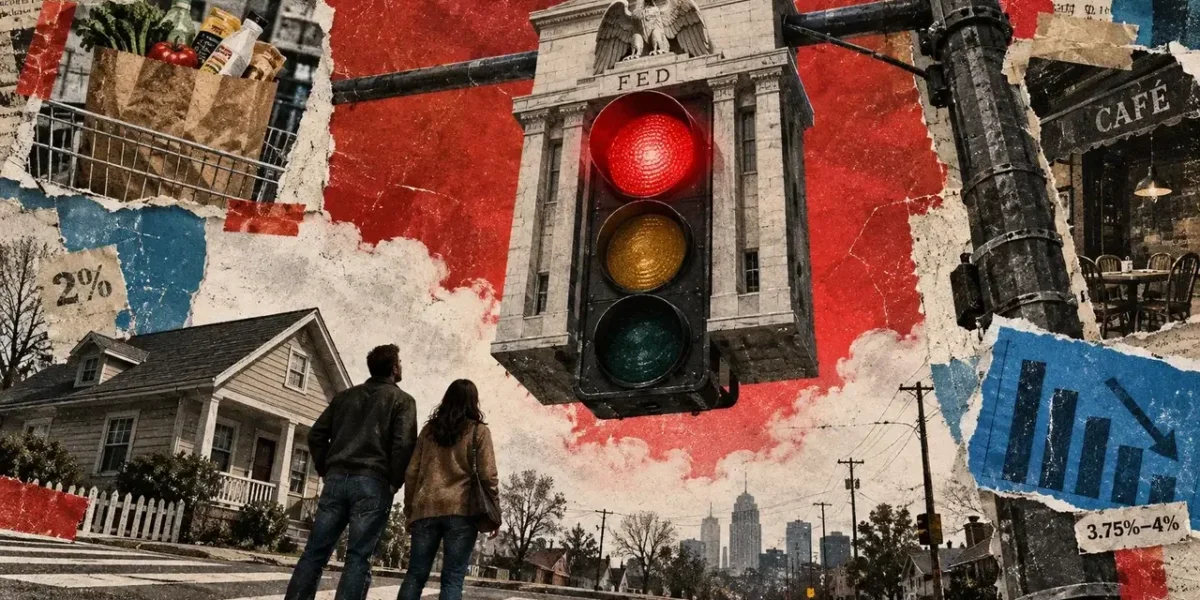
The Federal Reserve might halt its interest-rate increases before inflation officially hits the 2% objective, provided policymakers become convinced the economy is already moving toward that target independently.
The September gathering left the majority of officials unconvinced, as robust consumer spending and persistent price growth outweighed the financial pressure that costly borrowing inflicted on certain sectors.
Meeting minutes published on Oct. 7 shed light on the rationale behind the unanimous vote to push the benchmark interest rate to a range of 3.75%-4%.
While the majority of participants anticipated another rate increase before the conclusion of the year, their motivations varied: numerous officials viewed higher rates as a safeguard against sticky inflation, whereas others believed the economic environment necessitated higher borrowing costs regardless.
Although these perspectives frequently overlap, they offer different thresholds for persuasion. Proof that temporary price spikes are subsiding might satisfy those seeking an insurance policy against inflation, whereas policymakers concerned about excessive spending would additionally need to witness consumers and corporations curtailing their outlays.
This dialogue clarifies what factors might halt a subsequent rate increase, even though officials did not establish a definitive checklist of conditions that would completely rule one out.
Cheaper gasoline won’t do all the work
Higher interest rates drive up borrowing expenses and enhance the appeal of saving, which dampens certain expenditures and complicates efforts by companies to raise prices. These monetary policy impacts materialize gradually and affect sectors unevenly; prospective homebuyers may retreat from the market, while cash-rich corporations continue to deploy capital.
Because the central bank lacks the capacity to extract petroleum or eliminate import tariffs, lifting borrowing expenses cannot directly resolve the supply constraints responsible for particular price surges. Instead, the Fed can moderate overall spending enough to inhibit businesses from passing those costs along, thereby mitigating the danger that an initial price shock evolves into broad, entrenched inflation.
During the September discussions, officials pointed to elevated energy expenditures alongside heavy capital outlays for the equipment and data facilities required for artificial intelligence.
Certain enterprises demonstrated a greater capacity to transfer costs onto buyers, and multiple participants drew attention to ongoing price gains in non-housing services. While cheaper fuel would relieve some pressure on those firms, consumers who remain willing to spend could still enable businesses to elevate other prices.
Consistent reports indicating a moderation in price growth across various consumer goods would provide the Fed with stronger justification to hold off. Because declining inflation simply indicates that prices are advancing at a more gradual pace, grocery bills can still feel burdensome even as the aggregate data improves. Policymakers would search for tangible signs that companies are losing the ability or the necessity to continually mark up prices.
Officials would also need to differentiate genuine economic progress from methodological adjustments in how data is calculated. The minutes highlighted that an upcoming revision to inflation metrics will diminish the extent to which software pricing and investment-management fees contribute to the reported figure.
While refined measurement enhances policy formulation, a reduced reading stemming merely from a recalculated formula does not imply that commercial enterprises have curtailed their actual price increases.
Policymakers expressed confidence that the public still anticipates inflation converging toward the 2% objective over the long run, though they maintained concerns that prolonged periods above that threshold could prompt laborers to demand larger wages and corporations to formulate larger price hikes.
If price pressures ease across a broader swath of the economy while inflation expectations remain anchored, officials would have less incentive to enact precautionary rate increases ahead of the target date.
The jobs market doesn’t have to collapse to count
The central bank’s statutory mandate to foster maximum employment serves as a boundary on how aggressively it can raise borrowing costs.
At the September gathering, participants generally characterized the labor market as stable with low joblessness, and most believed labor conditions had strengthened somewhat, granting the Fed latitude to combat inflation.
Certain individuals argued that compensation was expanding at a pace consistent with a return to 2% inflation, or maintained that the employment sector was not actively fueling inflationary pressures. Several others remarked that both hiring activity and layoffs remained unusually subdued, while unemployed individuals encountered persistent challenges securing new positions.
A low volume of layoffs can project an illusion of economic health to individuals who retain their jobs, whereas stagnant hiring creates severe hardships for those searching for work. Should employers begin trimming headcounts before hiring accelerates, displaced workers will find severely limited alternatives, potentially transforming a stable jobless rate into a much more troubling scenario.
A sustained climb in unemployment accompanied by widespread layoffs would render another rate increase difficult to defend, even if inflation failed to recede as much as policymakers desired. Because a single monthly employment report could capture temporary fluctuations or undergo subsequent revisions, evidence spanning multiple reports would carry greater analytical weight than any isolated statistic.
Cooling inflation paired with resilient employment would furnish the Fed with a compelling rationale to halt tightening. In September, officials generally assigned roughly equal probabilities to employment performing better or worse than anticipated, whereas inflation was viewed as carrying a higher risk of remaining excessive.
Persistently sluggish hiring or accelerated job destruction would offer sufficient justification to reassess the policy stance without waiting for an official recession to materialize.
Your mortgage rate can feel expensive while money still flows
Several officials asserted that prevailing interest rates were exerting minimal restraint on economic activity, despite punishing mortgage terms and severe financial strain on lower-income households.
A wide range of businesses retained access to credit, investments in artificial intelligence remained robust, and surges in the stock market sustained consumption among wealthier demographics.
Individuals struggling to purchase homes and corporations financing expansion projects experienced vastly different economic realities. The central bank is tasked with determining whether their aggregate spending is decelerating sufficiently to pull inflation down, which explains why painful borrowing costs in the housing sector do not automatically dictate monetary decisions.
Economists define the neutral interest rate as a theoretical level that neither accelerates nor restrains economic momentum, though determining its exact location requires estimation. Two policymakers lifted their projections for that neutral rate, signaling their belief that a higher nominal interest rate was necessary to achieve an equivalent degree of economic cooling.
Should commercial lenders adopt more conservative underwriting standards and consumer spending begin to cool, policymakers would secure proof that existing borrowing expenses are actively fulfilling their purpose.
Market interest rates can likewise ascend independently of central bank action, though long-term borrowing costs do not automatically mirror shifts in the short-term rate governed by the Fed. Officials would need to observe those financial conditions genuinely suppressing credit creation and consumer outlays.
Lower inflation coupled with a durable labor market could encourage investors to anticipate cheaper credit while maintaining their appetite for Bitcoin and other volatile risk assets. Conversely, if mounting job losses and credit constraints compelled the Fed to implement a pause, investors might liquidate those holdings to preserve capital in cash.
Opting to maintain steady rates would not equate to a promise of imminent rate cuts or a return to cheap financing. Officials scheduled their subsequent gathering for Oct. 27–28, with these minutes simply reflecting their collective assessment from September.
Evidence that price growth is moderating without the need for further monetary tightening would provide a rationale to pause, whereas clear signs of rising job losses would make additional rate hikes indefensible—leaving Bitcoin investors with little cause for optimism.
Frequently Asked Questions
01What is the Federal Reserve’s inflation target?
The Federal Reserve aims for a long-run inflation rate of 2% as measured by the annual change in the personal consumption expenditures (PCE) price index.
02Does inflation dropping to 2% mean prices are going down?
No. When inflation falls, it simply means that prices are rising at a slower pace than before, rather than declining overall.
03What is the neutral interest rate?
The neutral interest rate is the theoretical level of interest rates that neither stimulates nor restricts economic growth.