Being right about Bitcoin won’t save your 3x leveraged ETF position
Being right about Bitcoin may not save your 3x leveraged ETF position due to daily reset mechanisms. The SEC recently approved listing rules for proposed VS Trust products, highlighting the compounding risks and administrative burdens involved.

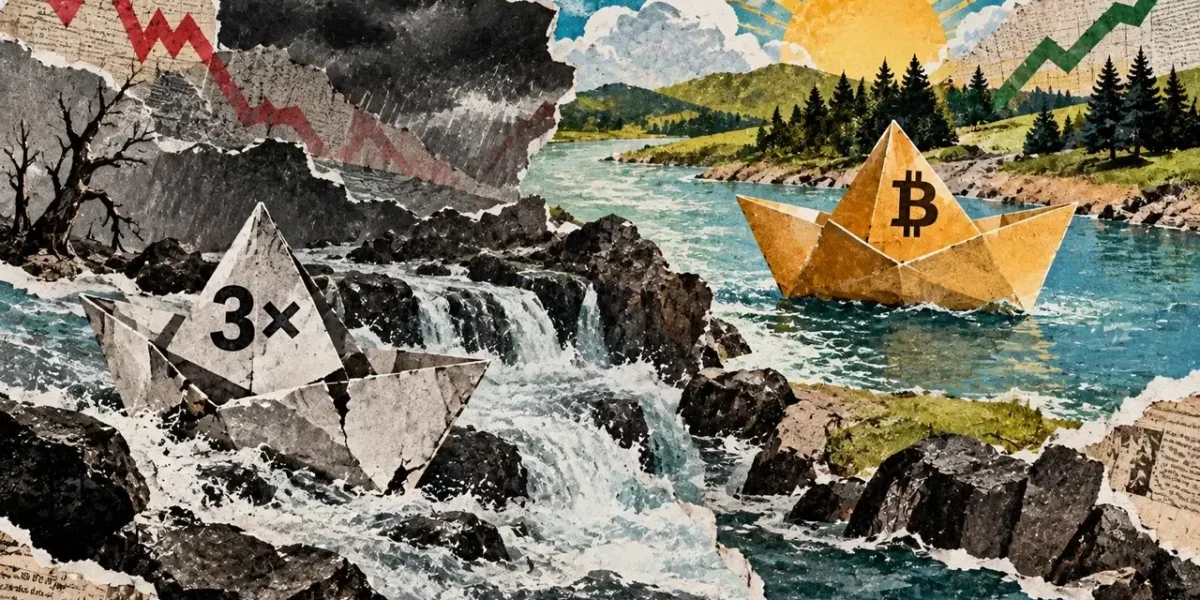
Even if Bitcoin’s eventual rebound proves your investment thesis correct, your leveraged fund could still remain deeply in the red. This happens because the daily reset mechanism of these products can turn waiting into a very costly endeavor.
Accurately predicting Bitcoin and successfully earning a profit from it are becoming two distinct capabilities, particularly as Wall Street develops new vehicles tailored for investors seeking more excitement than the standard asset provides.
On Oct. 2, the SEC granted approval to exchange-listing rules for proposed 3x Bitcoin and Ethereum funds managed by VS Trust. This regulatory step brings them closer to public trading, offering an appeal defined clearly by the multiplier: heightened exposure to a market you anticipate will rise.
However, what occurs in the interim between purchasing the fund and being vindicated? Bitcoin can drop, recover, and climb back to your initial entry price while a leveraged fund continues to accumulate losses—even while operating exactly as advertised.
That guarantee applies solely to a single day, representing a much shorter timeframe than many participants plan for their capital.
Your Bitcoin conviction doesn’t reset
The proposed funds aim to deliver three times the daily performance of their benchmark, excluding fees and expenses. Holding these assets for a month does not scale that promise to triple the entire month’s return, since each daily gain or loss serves as the foundational balance for the subsequent session.
While a Bitcoin investor contemplates the market’s position six months down the line, the fund constantly readjusts its exposure depending on the capital it holds on that specific day.
When market values drop, the leverage drains the fund’s capital at a faster rate than it decreases the magnitude of its market position. To maintain the targeted multiple, the fund scales back its exposure, resulting in a smaller footprint when a market recovery begins.
Subsequent gains then apply to that diminished balance, meaning a return of the underlying market to its previous peak does not necessarily restore the shareholder’s portfolio to its original level.
Conversely, during a market rally, profits supply the fund with additional capital, enabling it to assume greater exposure for the next trading session. Investors can leave their holdings untouched while the internal investment expands and contracts daily, completely detached from their long-term outlook on Bitcoin.
Within its investor bulletin regarding leveraged funds, the SEC highlights a documented four-month span where an unspecified index gained roughly 8%, while a fund targeting triple its daily return dropped 53%. Although this was neither a Bitcoin fund nor a prediction for these specific upcoming offerings, it illustrates the financial impact hidden behind standard prospectus warnings.
Daily compounding can also function to an investor’s advantage during a sustained upward trend, permitting a leveraged fund to yield returns exceeding three times the benchmark’s total gain. Because this mechanism benefits certain price trajectories while penalizing others, buyers must accurately forecast more than just the ultimate destination.
Bitcoin’s historical tendency to reward patient holders interacts poorly with this dynamic, given that a daily-reset fund continually recalculates the exposure supportable by your remaining capital.
The ETF wrapper comes with extra paperwork
Approval documents indicate that these funds utilize futures contracts, inserting an extra barrier between the spot price of Bitcoin followed by the public and the returns actually delivered.
Because futures operate with predetermined expiration dates, sustaining exposure requires rolling over contracts as they near maturity. Depending on the pricing structure between near-term and deferred contracts, replacing these agreements can either increase strategy costs or work to the fund’s benefit.
Regardless, simply multiplying the return of Bitcoin’s spot price by three will not replicate the performance of the fund.
An amended filing submitted by VS Trust on Oct. 7 outlines an annual management fee of 1.85% for both proposed products. The estimated trading return required to offset these expenses sits at 1.98% for the Bitcoin fund and 2.78% for the Ethereum fund, factoring in additional operational costs and projected interest earned on collateral.
Such breakeven figures outline the performance necessary to cover projected operational overhead under the filing’s baseline assumptions, all before investors generate any return on their risk.
Nevertheless, familiar exchange-traded structures arrive alongside less familiar administrative burdens. These vehicles function as commodity-pool products operating outside the regulatory framework of the Investment Company Act of 1940 that governs standard investment-company ETFs, with the filing indicating partnership tax reporting via Schedule K-1.
Consequently, shareholders might incur taxable allocations without ever receiving cash distributions, introducing an extra layer of complexity to a trade likely initiated for capital appreciation.
According to the Oct. 7 filing, the funds have not yet commenced trading, meaning none of these details reflect an actual performance history for tickers BITH or ETHK. While the listing authorization establishes a pathway to the market, the disclosures clarify what purchasers would genuinely own.
When a bad trade becomes a long-term investment
Traders seeking amplified short-term exposure who fully grasp the mechanics will find a clear appeal in these products. Buying shares directly with cash spares them the administrative effort of maintaining an independent futures margin account, though the underlying leverage remains active.
Complications arise when a short-term trade suffers losses and the holder decides to reclassify it as a long-term investment, as waiting for a Bitcoin rebound feels preferable to locking in a loss.
Even so, the fund persists in restructuring its position around the remaining capital inside it, irrespective of a shareholder’s choice to exercise patience. Even the prospect of waiting presumes that enough capital survives to participate in any subsequent recovery, with issuers explicitly warning that an entire investment can be wiped out in a single day or overnight.
Acquiring a 3x fund requires accepting continuous daily exposure adjustments alongside the distinct risk that a volatile market recovery will leave you trailing far behind the asset you accurately believed in.
Even if Bitcoin stages a full recovery, a fund utilizing a daily reset has no mandate to recover the money lost along the way. Investor conviction cannot compel a fund to calculate tomorrow’s returns using capital that vanished yesterday.
Frequently Asked Questions
- What is a 3x leveraged Bitcoin ETF? It is a proposed investment product designed to deliver three times the daily performance of its underlying benchmark, before fees and expenses.
- Why can a leveraged fund lose money even if Bitcoin recovers? Because these funds reset their exposure daily based on their current capital. Losses reduce the capital base faster than market exposure decreases, meaning subsequent gains apply to a smaller balance.
- Do these funds track the spot price of Bitcoin directly? No, they utilize futures contracts, which require rolling over expiring contracts and involve additional management fees, collateral considerations, and administrative paperwork like Schedule K-1 tax forms.
- What are the risks of holding these funds long-term? The daily compounding mechanism and volatility decay can cause long-term performance to deviate significantly from a simple 3x multiple of the underlying asset’s long-term return, with the potential for substantial capital loss.