A $7 billion crypto ETF plumbing boom just ran into the IRS
The IRS and Treasury Department are evaluating a crypto ETF tax strategy, targeting fund structures that might bypass taxable gains by leveraging in-kind redemptions and strict regulatory interpretations.

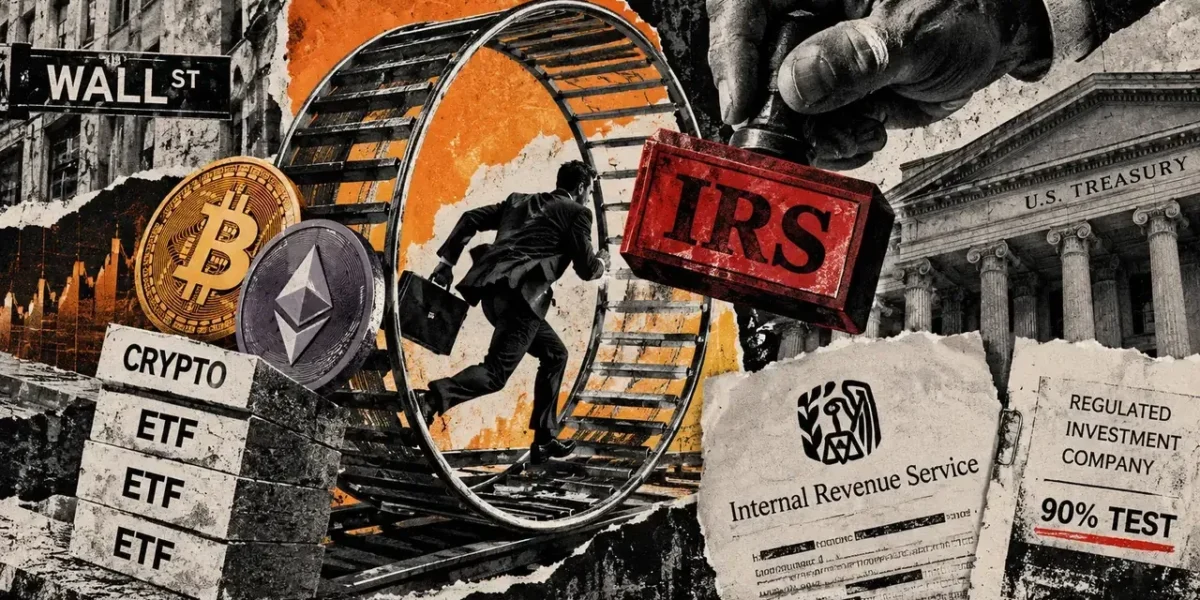
The Internal Revenue Service (IRS) is currently evaluating a crypto-linked exchange-traded fund (ETF) tax strategy as Washington steps up its efforts against financial structures intended to bypass taxable gains.
The IRS and the Treasury Department pointed to digital assets as a sector where fund managers might be stretching tax provisions past their original intent, which could lead to tighter enforcement or additional regulations.
Writing on X, Treasury Secretary Scott Bessent stated that the agencies are “serious about cracking down on transactions designed to dodge taxes or exploit our federal tax code,” framing the notice as part of a broader initiative targeting tax-driven investment tactics.
This development casts a new tax shadow over a crypto ETF market that has spent the past year embracing the in-kind mechanics traditionally utilized by standard funds. Last year, the Securities and Exchange Commission (SEC) greenlit in-kind creations and redemptions for spot crypto exchange-traded products, noting the change could minimize price slippage and lower costs.
While Treasury refrained from challenging conventional ETF redemptions, its focus lies on structures leveraging those specific transactions to secure tax outcomes that regulators believe may not align with a fund’s underlying economics.
Crypto enters the IRS crosshairs through a 90% tax test
At the center of the debate is a regulation governing regulated investment companies (RICs), which encompass a large portion of the US ETF market.
To retain favorable tax status, RICs generally must pull at least 90% of their annual gross income from qualifying categories, which include interest, dividends, and gains from stocks, securities, and certain currencies.
According to Treasury, some ETFs maintain that they can completely exclude gains from assets outside those specific groups from the calculation.
The official notice specifically highlights funds that hold commodities or digital assets, either directly or via grantor trusts. Instead of liquidating an appreciated asset, the fund can utilize it to settle an in-kind redemption requested by an authorized participant.
Pursuant to Section 852(b)(6), ETFs are generally permitted to distribute appreciated property during qualifying redemptions without triggering the embedded gain. Consequently, certain funds argue that this unrecognized gain should likewise be omitted when calculating whether they successfully met the RIC income test.
Treasury cautioned that this strategy could permit an ETF to restrict the income subjected to the 90% threshold, regardless of its true economic income, reflecting official skepticism regarding that specific interpretation.
This action does not constitute an outright ban. The government has solicited feedback on the practice and is weighing what subsequent steps, if any, are necessary.
This approach differs from another technique caught in the same regulatory review. Revenue Ruling 2026-20 dismisses certain prearranged deals where investors contribute appreciated securities to an ETF prior to quickly withdrawing those assets via redemptions, allowing those investors to exit with a different portfolio without immediately reporting the embedded gain.
Bessent adopted a stricter stance concerning these Section 351 conversions, declaring that these transactions “don’t work under existing law.”
The IRS noted that these arrangements can be reclassified as taxable exchanges, placing them further along in the government’s enforcement efforts compared to the digital-asset strategy highlighted in the parallel notice.
Crypto in-kind infrastructure has already reached billions
This regulatory attention follows a period where in-kind transfers swiftly evolved into a core component of the plumbing supporting US crypto investment products.
Based on its recent quarterly filing, BlackRock’s iShares Bitcoin Trust ETF (IBIT) distributed roughly $5.49 billion worth of Bitcoin via in-kind redemptions throughout the first six months of 2026. Approximately $3.85 billion of that total took place in the second quarter.
Meanwhile, its iShares Ethereum Trust ETF (ETHA) distributed another $1.72 billion in Ethereum through in-kind methods by June, bringing the combined six-month total for these two BlackRock offerings to about $7.22 billion.
During the same timeframe, IBIT also acquired roughly $9.36 billion in Bitcoin through in-kind creations, demonstrating how rapidly direct cryptocurrency transfers between funds and authorized participants have grown since the SEC moved away from the cash-only framework.
These specific transactions do not imply that BlackRock is actively utilizing the strategy flagged by the Treasury.
Both IBIT and ETHA function as grantor trusts for federal income tax purposes, meaning any gains and losses flow directly through to shareholders rather than triggering the RIC income test targeted by the IRS notice.
Even so, their transaction volume illustrates the vast scale of infrastructure currently accessible to funds aiming to transfer crypto in kind.
Treasury’s concerns target a distinct segment: RICs that acquire digital-asset exposure—either directly or via structures like grantor trusts—and subsequently deploy redemptions to clear out appreciated positions whose gains might otherwise complicate the 90% evaluation.
This distinction could gain importance as asset managers weave crypto exposure into actively managed, multi-asset, and income ETF strategies rather than relying strictly on standalone Ethereum or Bitcoin products.
Fund managers may face scrutiny before new rules arrive
The Treasury has maintained several potential avenues for its next steps.
Notice 2026-62 indicates that regulators could respond through revenue rulings, regulations, or alternate guidance, and may designate specific setups as listed transactions or transactions of interest—classifications that carry heavier reporting obligations.
Any forthcoming guidance would not necessarily be restricted to future trades.
The agencies clarified that future actions could be prospective or, where legally permissible, retroactive to deals finalized prior to the issuance of the guidance. Furthermore, the IRS cautioned that it can challenge aggressive investment-fund strategies during audits under existing laws without waiting for the introduction of new rules.
As a result, managers relying on crypto-linked RIC structures may need to evaluate their exposure ahead of any formal standardization by the Treasury.
Funds whose tax advantages rely on stripping out appreciated digital assets via redemption baskets could experience pressure to justify the economic rationale behind those transactions, alter how baskets are structured, or scale back arrangements that depend on omitting those gains from RIC income calculations.
For product sponsors building the next wave of crypto-linked ETFs, this uncertainty introduces a fresh constraint. Frameworks that appeared tax-efficient under current interpretations may now demand alternative portfolio mechanics, extra legal opinions, or an increased safety margin prior to launch.
Frequently Asked Questions
01What is the main concern of the IRS regarding crypto ETFs?
The IRS is examining whether certain crypto-linked ETFs are improperly excluding gains from assets outside qualifying categories when meeting the 90% gross income test required for regulated investment companies (RICs).
02Are all crypto ETFs targeted by this IRS notice?
No. Grantor trusts like BlackRock’s IBIT and ETHA pass gains and losses directly to shareholders and are not subject to the specific RIC income test at the center of the IRS notice.
03Does the Treasury’s notice ban in-kind crypto redemptions?
No. The government stopped short of banning conventional ETF redemptions and is currently requesting information and considering potential future actions.