AI may be keeping Bitcoin’s biggest macro headwind alive after the Fed stops hiking
Massive private debt issuance and infrastructure expenditures for the artificial intelligence boom are driving Treasury yields upward, creating a persistent macroeconomic headwind for Bitcoin even after Federal Reserve rate hikes stop.

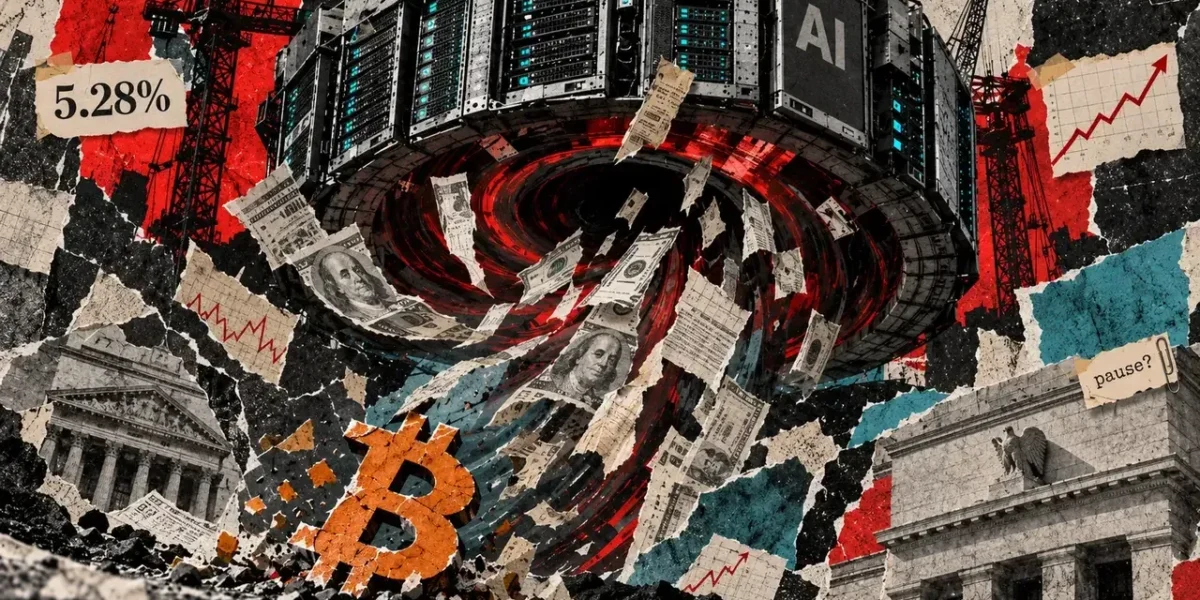
Bitcoin is confronting an alternative macroeconomic obstacle stemming from the artificial intelligence boom, as massive infrastructure expenditures vie for long-term capital.
According to the minutes from the Federal Reserve’s Sept. 15–16 gathering, market participants highlighted heavy private debt issuance dedicated to AI infrastructure as a key driver pushing Treasury yields and term premiums upward. Across maturities spanning two to 10 years, nominal yields climbed by roughly 35 basis points between Fed meetings.
This dynamic complicates matters for cryptocurrency investors whose focus centers primarily on when the central bank will halt its monetary tightening. Policymakers lifted the federal funds target by 25 basis points to a range of 3.75%–4% in September, with the majority of officials indicating that an additional increase would likely be warranted before the conclusion of the year.
Even once that cycle concludes, persistent competition for long-term financing could sustain elevated borrowing costs independently of the overnight policy rate.
AI borrowing creates pressure beyond the Fed
The scale of these financing demands has already grown large enough to draw the attention of regulators and policymakers.
Estimates from the Bank for International Settlements (BIS) suggest that the five largest technology companies will direct more than $1 trillion toward AI-related capital expenditures across 2025 and 2026. Furthermore, industry projections referenced by the BIS place current global AI investment at approximately $500 billion, with the potential to scale between $3 trillion and $4 trillion by the year 2030.
While much of the initial groundwork could be sustained via corporate cash flows, that financial balance is shifting. As spending outpaces earnings and free cash flow among certain enterprises, reliance on corporate bonds and private credit is intensifying. The BIS noted that debt is becoming a more prominent component of the financing mix as firms construct data centers, acquire specialized chips, and secure necessary energy infrastructure.
The manager of the Fed’s trading desk reported that spreads on debt issued by major cloud computing providers remained wide, driven by substantial borrowing volumes and long maturities. Market contacts similarly pointed directly to capital competition from AI-related private debt issuance as a contributing factor to rising Treasury term premiums.
Although the meeting minutes did not quantify the precise portion of the roughly 35-basis-point yield increase directly attributable to AI financing, other factors were also cited, including stronger economic data, expectations of continued Fed tightening, geopolitical developments, and uncertainty surrounding Treasury buybacks.
Nevertheless, this structural mechanism establishes a potential headwind for Bitcoin even after the overarching policy-rate cycle shifts.
Data from the Treasury Department indicated that the 10-year Treasury par yield sat at 5.28% on Oct. 7, while the inflation-adjusted 10-year real yield registered at 2.92%. Such levels afford investors a substantial, guaranteed return derived from government securities, entirely circumventing the volatility and drawdown risks intrinsic to Bitcoin.
Within the crypto landscape, this environment elevates the required rate of return for risk-on assets. A prospective pause in Fed rate hikes could temper short-term rate expectations without offering equivalent relief at the long end of the yield curve if corporations maintain aggressive competition for external financing.
Additionally, the Federal Reserve observed that shifts in real interest rates accounted for the majority of the upward movement in longer-dated Treasury yields during the intermeeting window.
This distinction holds vital importance for Bitcoin because real yields denote the return accessible after accounting for inflation. This sharpens the competition between an asset lacking contractual cash flows and securities capable of delivering positive inflation-adjusted income.
Thus far, AI-linked equities have absorbed these heightened financing costs with greater ease. The Fed noted that companies directly benefiting from infrastructure investments outperformed the broader market, as robust actual and expected earnings supported equity valuations despite contracting valuation multiples.
The same boom could eventually reverse course
Looking further ahead, the long-term risk centers on whether this intensive investment race succeeds too well in generating excess capacity.
The BIS has issued warnings indicating that the current AI buildout ranks among the largest technology investment booms in the history of the United States. Its research contends that aggressive competition for future market share could compel corporations to commit capital far exceeding what eventual returns can justify. Simultaneously, heavier reliance on debt amplifies the vulnerability to financial distress and forced asset liquidations if revenue trajectories fall short of expectations.
This dynamic introduces a secondary, distinctly different scenario for Bitcoin.
Arthur Hayes, co-founder of the defunct BitMEX exchange, argues that the race to build data centers will inevitably culminate in a glut of computing capacity and a subsequent market downturn.
Hayes has repeatedly emphasized that major historical technological rollouts have characteristically suffered from overbuilding, anticipating that financial distress will materialize as new capacity comes online—potentially around late 2027 or 2028.
His analytical thesis for Bitcoin commences right where current yield pressures leave off. Should an AI market correction threaten heavily leveraged infrastructure owners, Hayes projects that policymakers will ultimately intervene with liquidity injections, thereby fostering an economic climate he asserts would benefit Bitcoin and alternative cryptographic assets.
Of course, that trajectory remains speculative. AI demand could scale rapidly enough to fully absorb the infrastructure currently under construction, while elevated productivity and profits could justify the outlays well before debt obligations become burdensome.
Even so, the BIS views the prevailing financing structure as a genuine vulnerability. Because investment commitments increasingly outpace internally generated cash, future revenue performance becomes drastically more critical to a firm’s capacity to service the capital secured for the buildout.
Bitcoin’s next macro test moves to the long end
For participants in the Bitcoin market, the immediate tactical signal is consequently less about the specific policy meeting where the Federal Reserve ceases rate increases and more about the subsequent trajectory of long-term real yields.
A sustained decline in the 10-year yield alongside a lower term premium would undermine the argument that AI capital demands are persistently keeping financial conditions tight. Conversely, robust spot demand for Bitcoin amidst persistently elevated yields would demonstrate that investors remain willing to absorb higher opportunity costs.
The latter combination would prove significantly more challenging for digital asset markets. Persistent AI-related borrowing running concurrently with high real yields would leave government debt and corporate credit fighting aggressively for marginal capital even after monetary tightening cycles peak.
The Federal Reserve’s upcoming meeting is slated for Oct. 27–28, with officials remaining focused on inflation metrics and the potential for a subsequent rate increase prior to year-end.
For Bitcoin, however, the paramount test may well unfold after the final rate hike concludes. If the AI investment boom keeps the long end of the Treasury yield curve elevated, traders anticipating monetary relief from a Fed pause could find those expectations weaker than in prior economic cycles. Should the spending boom ultimately fracture, investors will be forced to monitor whether ensuing financial stress triggers the exact liquidity response that figures like Hayes are already positioning to capture.
Frequently Asked Questions
- How does the AI boom affect Bitcoin? Massive infrastructure spending by AI companies drives up private debt issuance, pushing Treasury yields and term premiums higher. This increases the opportunity cost of holding non-yielding assets like Bitcoin.
- Why are long-term Treasury yields rising? Increased capital demands from technology firms building data centers and chips require significant corporate debt financing, creating competition for long-term financing that keeps borrowing costs elevated.
- What does the BIS say about AI investments? The Bank for International Settlements warns that the AI buildout is one of the largest tech booms in US history, noting that heavy reliance on debt could lead to financial stress if revenues disappoint.