CFTC makes its biggest move yet to bring offshore crypto trading back to the US
The Commodity Futures Trading Commission has introduced a federal pathway allowing US cryptocurrency exchanges to offer retail leverage, creating a new regulatory structure to bring offshore trading back.

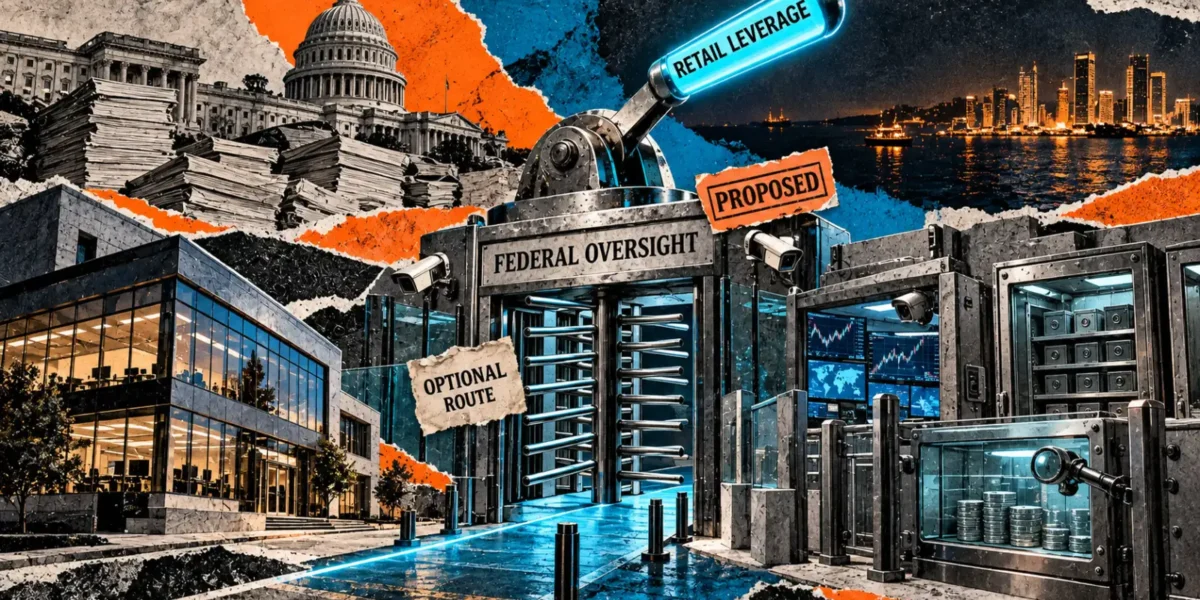
The Commodity Futures Trading Commission (CFTC) has introduced a federal pathway allowing US cryptocurrency exchanges to offer retail leverage, stepping in as Congress continues to experience gridlocks regarding comprehensive market-structure legislation.
On Oct. 5, the financial regulatory body launched rulemaking for Regulation Crypto Asset Transactions (CTX) and Regulation Crypto Asset Markets (CAM). This move establishes a national regulatory structure for trading platforms that offer retail clients margined, financed, or leveraged crypto transactions.
Because the agency acknowledges it cannot force the broader digital asset market onto CFTC-regulated venues without direct congressional action, participation for standard spot exchanges remains entirely optional. The primary incentive for platforms to join is the ability to offer leveraged products—a privilege that traditional state money-transmitter licenses alone do not grant.
This initiative enables the CFTC to utilize powers it asserts are already authorized under the Commodity Exchange Act, bypassing the current absence of overarching federal legislation for crypto spot markets.
CFTC turns leverage into its regulatory carrot
The proposed framework would establish three distinct regulatory paths depending on the specific offerings an exchange wishes to provide to US clients.
Traditional spot exchanges could continue operating mainly under state-level licensing structures, reinforced by the existing anti-fraud and anti-manipulation powers of the CFTC.
Meanwhile, platforms looking to provide leveraged or financed retail crypto transactions can seek federal registration through the new framework. Venues focusing on futures, perpetual contracts, and other derivatives will remain governed by the agency’s current designated contract market rules.
The CAM designation is designed to occupy that middle tier.
This setup permits existing designated contract markets to offer CTXs under customized guidelines while giving other crypto platforms a separate route to federal supervision without forcing them to function as traditional derivatives exchanges.
The CFTC bases this approach on Section 2(c)(2)(D) of the Commodity Exchange Act, which addresses specific leveraged retail commodity transactions.
According to the Hyperliquid Policy Center, the resulting architecture could present a more transparent regulatory ladder: state licensing for baseline spot trading, federal CFTC oversight where leverage is introduced, and the existing derivatives regime for perpetuals and futures.
Furthermore, this proposal could help close a major product discrepancy separating US exchanges from their overseas competitors.
Offshore venues have historically captured significant trading volume and active traders by offering perpetual contracts and leveraged trading. Due to strict domestic regulatory limits, US platforms have typically maintained restricted product menus.
This dynamic forms the core commercial trade-off.
While federal registration could grant domestic exchanges access to instruments that have historically boosted the business models of foreign rivals, accepting CFTC supervision may also force modifications to the vertically integrated setups where many crypto platforms combine custody, brokerage, and exchange services.
Larry Florio, deputy general counsel for synthetic-dollar creator Ethena Labs, highlighted retail leverage as the main draw of the proposal, suggesting it might be powerful enough to entice exchanges into a unified federal framework voluntarily.
Ultimately, the number of major platforms that adopt the regime may depend on whether the additional revenue and volume generated by leverage outweigh these compliance constraints.
FTX shapes the cost of opting in
The regulatory compromise involves much more than just receiving authorization to offer leverage.
CFTC Chairman Michael Selig anchored the initiative around lessons learned from the collapse of FTX, arguing that regulators must build preventive safeguards rather than relying primarily on punitive enforcement after consumer assets are lost.
Stating on Oct. 5 that “the lesson from FTX’s failure should have been obvious,” Selig emphasized that shielding customers from fraud must go hand-in-hand with fostering responsible crypto innovation.
Under the CAM structure, operators would encounter rigorous standards typically reserved for designated contract markets, such as protocols overseeing operational safeguards, conflicts of interest, market surveillance, and financial integrity.
Additionally, the agency is weighing crypto-specific mandates.
Exchanges could be obligated to evaluate vesting schedules, token concentration, distribution strategies, lockups, buybacks, and programmatic issuance when deciding if a specific asset can be traded safely without being vulnerable to market manipulation.
Platforms storing user assets in omnibus accounts might also be subjected to proof-of-reserves requirements—a preventive measure Selig explicitly tied to the vulnerabilities brought to light by FTX.
In addition, customer trades executed under CTX would be routed through registered futures commission merchants (FCMs), placing user accounts and assets under strict capital, segregation, and disclosure rules.
Involving FCMs would also bring client-facing operations under the scope of Bank Secrecy Act mandates, incorporating anti-money laundering controls, suspicious-activity reporting, and customer identification procedures.
These conditions elevate the true price of entering the federal framework beyond simple registration expenses or staffing costs for compliance. While exchanges gain the ability to offer leverage, they must surrender some of the operational flexibility that previously allowed them to house trading, brokerage, and custody under one roof.
This specific compromise will largely dictate whether the framework successfully attracts prominent US exchanges whose participation is vital for achieving true market scale.
CFTC draws a boundary around onchain markets
Beyond centralized platforms, the commission is beginning to map out how software developers and decentralized markets intersect with federal commodities law, although this effort exists somewhat outside the core CTX and CAM initiative.
The CTX proposal aims to clarify the “actual delivery” exception outlined in the Commodity Exchange Act. It would generally deem transfers of leveraged retail commodities to a customer’s external non-custodial wallet within a 28-day window as fulfilling the exemption from standard exchange-trading requirements.
On a separate note, Selig mentioned that the agency is evaluating appropriate treatments for developers who distribute software code without executing customer orders, handling user assets, or managing trade execution.
He noted:
“A person should not have to register as an introducing broker simply because that person shipped code.”
To that end, the CFTC is consulting with developers to determine where true control lies within onchain platforms and precisely when software-based activities begin to mirror regulated financial intermediation.
Nonetheless, the more pressing concern for centralized platforms remains purely economic.
Because the Oct. 5 action represents an advance notice of proposed rulemaking, the agency is actively gathering public feedback before formalizing comprehensive rules regarding leverage limits, asset eligibility, reserve practices, custody standards, and intermediary requirements.
Consequently, many critical components of the framework remain unfinalized, including exact capital standards, leverage restrictions, and the full extent to which FCM intermediation might alter current exchange business models.
Furthermore, regulatory agency rules lack the permanence of acts passed by Congress, meaning a subsequent commission retains the power to alter them.
Ultimately, the CFTC is putting a straightforward theory to the test: whether access to federally sanctioned retail leverage is compelling enough to convince crypto exchanges to embrace significantly deeper regulatory oversight.
If major trading venues conclude that it is, the agency could successfully pull trading volumes currently concentrated on foreign platforms back into regulated US markets, bypassing the ongoing legislative deadlock surrounding spot-market crypto jurisdiction.
Frequently Asked Questions
01What is the main goal of the CFTC’s new crypto framework?
The CFTC’s initiative aims to provide a federal pathway for US crypto exchanges to offer retail leverage, bringing offshore crypto trading back into the regulated domestic market while establishing preventative safeguards inspired by past market failures like FTX.
02Is participation in the new CFTC framework mandatory for crypto exchanges?
No, participation is entirely optional for standard spot exchanges. The agency acknowledges it cannot compel the wider crypto market onto CFTC-regulated venues without congressional action, so compliance is incentivized by access to regulated leveraged products.
03What role do futures commission merchants (FCMs) play in the CTX proposal?
Customer CTX trades would be intermediated through registered FCMs, bringing customer property and accounts under strict capital, segregation, and disclosure requirements, alongside mandatory Bank Secrecy Act and anti-money laundering controls.
04Are agency rules permanent under this rulemaking?
No, agency rules are less durable than legislation passed by Congress, meaning a future commission retains the authority to revise them.