Evernorth’s Nasdaq XRP treasury is approved, but its real buying power isn’t the $300 million expected
Roughly $88.5 million in closing-linked gross sources remains conditional, with expenses and spending choices deciding additional XRP demand. The post Evernorth’s Nasdaq XRP treasury is approved, but its real buying power isn’t the $300 million expected appeared first on CryptoSlate.

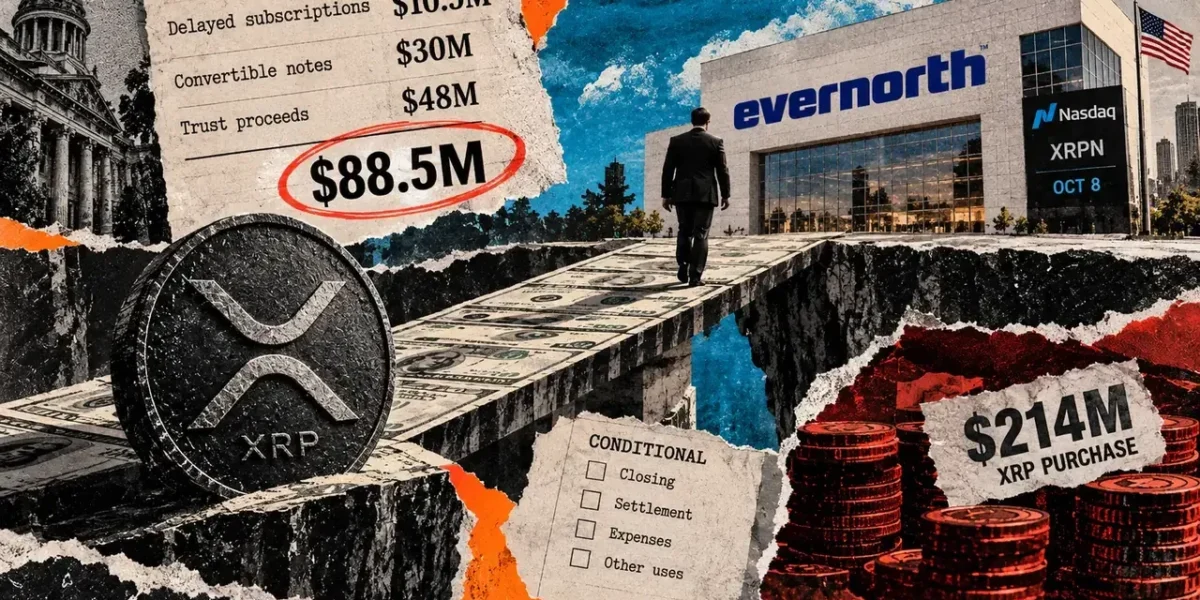
Following a shareholder vote that advanced its strategy to establish a publicly traded XRP treasury, Evernorth’s upcoming token acquisition depends heavily on the cash remaining at the transaction’s completion. A breakdown of disclosed delayed subscriptions, conditional notes, and projected trust proceeds points to roughly $88.5 million in gross financial sources assuming all three settle successfully, prior to accounting for expenses and alternative uses.
Evernorth and its merger partner, Armada Acquisition Corp. II, reported on October 1 that shareholders greenlit the combination on September 30. They anticipate finalizing the merger on October 7, contingent on remaining conditions, which will lead to the combined entity’s Class A shares trading on Nasdaq under the ticker XRPN starting October 8.
This timeline brings scrutiny to the company’s funding capabilities. The headline figure of approximately $300 million in gross cash features a private placement program whose early funding previously supported a roughly $214 million XRP purchase disclosed in November 2025. Funds already converted into digital assets cannot be deployed toward a subsequent acquisition.
XRP traded near $1.53 on CryptoSlate’s market page around press time.
Cash raised and cash still to settle
The announcement on October 1 outlines $225 million derived from related private placements, $30 million from incremental convertible-note financing, and an estimated $48 million in trust proceeds, all calculated prior to transaction expenses. These individual components aggregate to about $303 million, meaning the company’s summary figure of roughly $300 million should be understood as an approximation.
The definitive proxy separates the private placement figures into $214.05 million in advance cash subscriptions alongside $10.5 million in delayed cash subscriptions. Combined, these cash commitments amount to $224.55 million, aligning with the rounded $225 million placement metric provided in the release. Furthermore, these subscriptions incorporate distinct XRP contributions.
The historical capital outlay is substantial. In a disclosure dated November 4, 2025, Evernorth indicated it bought approximately 84.37 million additional XRP tokens at a mean price of about $2.54, translating to a roughly $214 million purchase financed via its advance placement proceeds.
This previous expenditure clarifies why the initial financing headline cannot be translated directly into a forecast for immediate spot market demand. The advance cash was already utilized to fund the 2025 acquisition. The November 2025 announcement lacks a specific current balance for unused advance cash, and a rounded purchase valuation cannot determine that remaining balance.
The identifiable sources tied to the closing can be distinguished from past allocations:
| Cash source | Disclosed amount | Condition or limitation |
|---|---|---|
| Delayed cash subscriptions | $10.5 million | Subject to subscription and combination closing conditions |
| Incremental convertible notes | $30 million | Issuance and payment conditioned on the business combination |
| Expected trust proceeds | Approximately $48 million | Company’s October 1 estimate, before transaction expenses |
Summing these figures yields roughly $88.5 million in gross sources if they settle according to expectations. This analytical gross total neither represents a net purchase budget announced by the company nor sets an upper boundary. Operating needs, expenses, and alternative obligations deplete deployable cash reserves, and any unspent advance cash remains unquantified.
The financing agreements remain conditional. Armada’s financing disclosure from September specifies that the issuance of the $30 million note relies upon, and is anticipated to happen concurrently with, the completion of the business combination. While shareholder approval satisfies one condition, it does not guarantee that the investor funds have materialized.
Costs and allocation preferences also play a critical role. The proxy allows net subscription proceeds and trust capital to support working capital, general corporate functions, and XRP acquisitions. Similarly, the note agreement permits general corporate applications, encompassing XRP purchases and other activities within the broader XRP ecosystem. Consequently, ecosystem spending cannot automatically be treated as a direct spot-token buy.
Past liabilities also require reconciliation. Armada’s balance sheet as of June 30, 2026, outlined around $5.39 million in accrued expenses and accounts payable alongside a $9.2 million deferred underwriting fee liability. These represent historical SPAC figures rather than the final closing expense outline for the merged enterprise; furthermore, the underwriting disbursement is contingent upon trust assets remaining post-redemption.
The convertible financing also introduces a debt obligation. Evernorth’s filing on September 17 outlines a 4% annual payment-in-kind interest structure that accumulates onto the principal, reaching maturity in 2031 absent earlier conversion, repurchase, or redemption per the terms. Securing this capital broadens potential cash availability while increasing debt liabilities, but it does not inherently signify a token purchase.
The 473 million XRP forecast is a starting position
Evernorth anticipates holding approximately 473 million XRP upon closing. This metric merges a distinct set of considerations: prior acquisitions, in-kind contributions from investors, and tokens that have fully settled into the treasury reserves.
The disclosure from November 2025 previously referenced over 473 million XRP as acquired and committed. Because of this, the comparable closing estimate cannot be framed as 473 million newly secured tokens generated by the September vote. Because the legacy figure incorporated commitments, it cannot independently verify current finalized holdings.
The proxy outlines the contribution pathway, highlighting an independent 50 million XRP related-party subscription alongside roughly 211.3 million XRP contributed via the sponsor by RippleWorks. RippleWorks retained the option to pull back its investment if the business combination fell through. These contractual allocations contrast with deploying corporate cash to acquire XRP directly on the open market.
Consequently, an updated holding report requires thorough reconciliation rather than a simple headline token tally. An increase driven by contributed XRP can expand treasury assets without demonstrating a concurrent cash purchase. Similarly, a rising dollar valuation of pre-existing tokens does not constitute token accumulation.
CryptoSlate’s reporting on September 28 focused on redemption risks impacting Evernorth’s financial backing. The October 1 estimate of trust proceeds advances the narrative toward anticipated closing cash levels while leaving final deductions and actual deployments to be determined.
The next meaningful indicators will be tangible. An announcement confirming a finalized merger and settled financing will verify the arrival of projected funds. A clear net cash balance combined with a paid-expense ledger will demonstrate what capital survived the transaction. Acquisition disclosures mapping cash outflows directly to purchased token volumes will reveal if those funds transformed into additional XRP.
A comprehensive holdings reconciliation would reinforce these findings by separating market purchases from in-kind contributions and auxiliary treasury operations. Disclosed allocations for operations and ecosystem development would clarify whether certain funds supported general business functions rather than executing new spot purchases.
Nasdaq share turnover addresses a separate dynamic. Within standard secondary trading, value transfers between the buyer and seller of the shares, meaning the issuer does not capture that trading volume as fresh treasury liquidity. Capital-raising initiatives that inject fresh corporate proceeds, allocations designated for XRP, and executed purchases remain distinct operational phases.
Regarding overall XRP demand, the most critical metric remains the volume of settled cash Evernorth ultimately directs toward buying additional tokens.
Frequently Asked Questions
- What is Evernorth’s Nasdaq ticker? Class A stock of the combined company trades on Nasdaq under the ticker XRPN.
- How much gross cash source is expected at closing? Disclosed delayed subscriptions, conditional notes, and expected trust proceeds indicate roughly $88.5 million in gross sources if all three settle before expenses.
- What was Evernorth’s previous major XRP purchase? In November 2025, Evernorth reported purchasing about 84.37 million additional XRP for approximately $214 million, funded from advance placement proceeds.
- Does share turnover on Nasdaq provide new cash for the treasury? No. In ordinary secondary trading, consideration moves between the share buyer and seller, and the issuer does not receive that trading volume as fresh treasury cash.