Global watchdog warns the $300 billion stablecoin market could face bank runs even with full reserves
The Financial Stability Board warned that the $300 billion stablecoin market faces severe redemption crises and bank run risks if cross-border reserves become inaccessible during market stress.

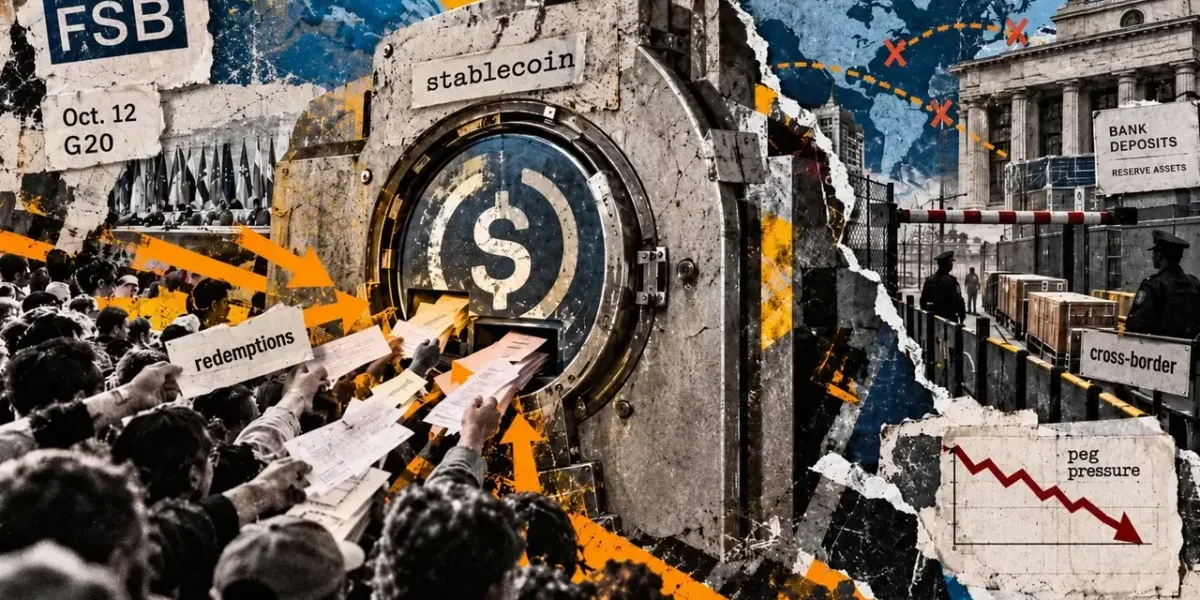
The Financial Stability Board (FSB) has cautioned that stablecoins could encounter redemption crises if market stress causes reserves to become inaccessible across international borders.
In a report published on Oct. 12, the international financial watchdog noted that stablecoin issuers utilizing affiliated entities across various countries might find it difficult to satisfy concentrated withdrawal requests when their underlying reserves are stored elsewhere.
This warning arrives just ahead of an Oct. 15 gathering of G20 central bank governors and finance ministers. Regulators are currently grappling with the escalating risks posed by a stablecoin sector valued at roughly $300 billion in mid-2026, with 99% of its total value tied to the US dollar.
FSB Chair Andrew Bailey pointed out that international regulatory coordination remains immature, leaving authorities unequipped with established frameworks to manage cross-border stablecoin failures.
Stablecoin reserves face cross-border stress test
Particular vulnerabilities were highlighted by the FSB regarding stablecoins that are issued by multiple affiliated companies sharing liability for a single token while keeping separate reserves.
Within such frameworks, holders may have the ability to redeem their tokens through any participating issuer, irrespective of the jurisdiction where the stablecoins were originally minted.
This flexibility can produce liquidity mismatches whenever redemption pressure concentrates heavily in one region while the majority of the collateral supporting those tokens sits in another.
Although shifting reserves between entities can alleviate these imbalances during normal periods, market panics can complicate transfers due to banking restrictions, settlement delays, and conflicting national regulations.
The rapid circulation velocity of stablecoins further magnifies these risks.
While digital tokens trade around the clock and travel globally, the traditional assets backing them—such as bank deposits and Treasury securities—remain bound by local financial market settlement procedures and operating hours.
According to the FSB, redemption delays could force holders to offload stablecoins at a discount on secondary markets, which might compromise their dollar pegs.
Furthermore, a severe enough run could spill over into traditional financial markets if issuers are forced to rapidly liquidate reserve assets or pull large bank deposits to fulfill redemption demands.
As an illustration of how cross-border reserve management impacts redemption processes, consider Circle’s European stablecoin framework.
Reflecting its updated September redemption policy, Circle co-issues USDC via a French entity designated for the European Economic Area alongside a US entity covering outside markets.
Under this policy, Circle France retains the ability to defer or modify specific redemption requests during defined stress scenarios if both entities fail to finalize reserve rebalancing.
Such measures may encompass temporary limits on redemptions for European crypto-asset service providers while still maintaining the fundamental rights of holders to redeem at par.
These contingency measures do not signal an active liquidity failure. Instead, they function under Circle’s unique jurisdictional redemption policies, which differ from the unrestricted cross-issuer redemption model outlined by the FSB.
Nonetheless, the regulator retains broader anxieties concerning the legal duties of affiliated issuers when a stablecoin experiences distress.
The FSB observed that because blockchain activity can be pseudonymous, issuers might struggle to pinpoint the storage locations of their tokens, complicating efforts to establish which specific entities bear responsibility for particular redemption claims.
Furthermore, discrepancies in national insolvency laws could introduce added uncertainty regarding which regulatory body possesses the authority to intervene and how remaining reserve assets should be distributed.
Uneven progress in regulatory development exacerbates these complications.
The FSB’s 2025 assessment uncovered significant shortcomings in how various countries have adopted its global stablecoin recommendations, granting issuers more opportunities to design operations across regions with differing supervisory standards.
FSB seeks stronger regulatory regime
Consequently, the watchdog is pushing for enhanced international information-sharing protocols, alongside stricter monitoring of token circulation paths, redemption locations, and reserve asset depositories.
Additionally, it urges regulators to evaluate secondary-market liquidity depth and forge synchronized strategies for managing stablecoin insolvency or distress.
However, regulators are hindered by prominent informational blind spots. The FSB noted that blockchain analytics firms frequently rely on divergent methodologies to gauge stablecoin activity, making it difficult to accurately track cross-border transactions and determine the geographic placement of holders.
The proposed guidelines expand upon the FSB’s 2023 recommendations and remain non-binding, meaning national regulators retain full discretion over implementation.
G20 officials will review these FSB findings during financial stability discussions at this week’s meeting.
Although the watchdog has outlined further initiatives focused on crisis planning, information sharing, and cross-border monitoring, it has not set a timeline for establishing unified procedures to handle multi-jurisdictional stablecoin failures.
Frequently Asked Questions
01What is the main concern the FSB highlighted regarding stablecoins?
The Financial Stability Board warned that stablecoins could experience redemption crises if market stress causes reserves held across borders to become inaccessible.
02How large is the stablecoin market?
The stablecoin market was valued at approximately $300 billion in mid-2026, with about 99% of its value pegged to the US dollar.
03Why do cross-border reserves create liquidity risks?
When redemption demand concentrates in one jurisdiction while collateral remains in another, banking restrictions, settlement delays, and regulatory differences can complicate the transfer of reserves during a market panic.
04Are the FSB’s recommendations binding for national regulators?
No, the FSB’s proposed measures are non-binding, leaving local authorities responsible for implementing any regulatory changes.