बिटकॉइन ने 5% यील्ड को तो सह लिया लेकिन क्रिप्टो का सस्ती-पूंजी वाला दौर नहीं टिक पाया
US Treasury यील्ड्स के कई वर्षों के उच्चतम स्तर पर पहुँचने और पारंपरिक वित्तपोषण मॉडल को चुनौती देने के बावजूद, मजबूत ETF इनफ्लो और लगातार संस्थागत आवंटन के कारण बिटकॉइन और एथेरियम ने तीसरी तिमाही में मजबूत लाभ दर्ज किया।

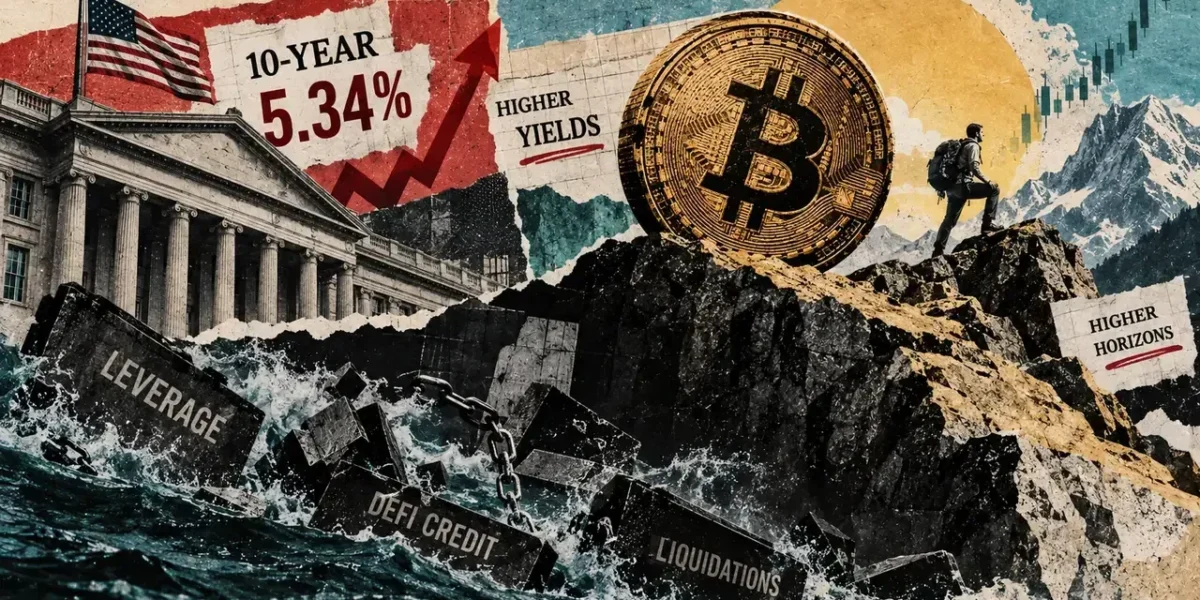
On Oct. 1, the US 10-year Treasury yield hit 5.34%, marking its highest point since 2002 and capping off a third quarter with an increase of nearly 90 basis points—the largest quarterly gain of this century. Over that exact three-month period, Bitcoin climbed approximately 43% and Ethereum advanced about 71%.
With Bitcoin currently trading in the mid-$80,000s, the clearest impact of this yield shock can be seen in the financing structures built around the cryptocurrency.
A 5% yield raises the bar, and Q3 buyers cleared it
According to the Federal Reserve’s H.15 release for Oct. 1, the 10-year yield stood at 5.29%, the 30-year at 5.64%, and the 10-year real yield at 2.93%. Consequently, inflation-adjusted government debt returns now directly compete with coupon-free digital assets.
Government bond yields advanced to fresh highs across the US, France, Germany, Japan, and the UK, where 30-year borrowing costs touched 6% for the first time since 1998. Simultaneously, Brent crude oil prices rose back above $100 per barrel.
Despite this challenging economic backdrop, US-traded spot Bitcoin ETFs attracted roughly $6.3 billion during the third quarter, while Ethereum ETFs brought in about $3 billion.
Citing increasing crypto activity, robust ETF inflows, and steady allocations from financial advisers and brokerages, Citi revised its 12-month Bitcoin price forecast upward from $82,000 to $113,000. Although higher yields remained a persistent headwind, overall demand sources outweighed them throughout the third quarter.
While a single quarter leaves the long-term correlation open to interpretation, ETF demand and adviser allocations clearly drove the outcome alongside shifting yields.
On Sept. 23, stronger-than-expected PMI data pushed yields higher, causing Bitcoin to drop below $85,000. This move resulted in $135.8 million in long liquidations occurring within a single hour, totaling $510 million over a 24-hour window.
A separate energy shock involving oil prices, bond yields, and Federal Reserve expectations sparked roughly $568 million in forced liquidations. Even so, the broader quarterly trend survived both shocks, while leveraged traders bore the brunt of the damage.
Bitcoin leverage gets repriced
By Sept. 25, open interest across selected exchanges dropped by 14.3% as Bitcoin hovered near $84,000 and the 10-year yield sat at 5.22%. Higher benchmark interest rates elevate the cost of capital for both direct borrowing and implicit leverage tools, including perpetual futures, basis trades, options structures, and collateralized loans.
At the same time, broader macroeconomic shocks amplify market volatility enough to force rapid deleveraging even in the middle of an ongoing bull run.
Data from Skadden shows that Bitcoin treasury companies typically fund their acquisitions via common equity, preferred stock, and convertible debt. This business model functions effectively when company shares trade at a premium to their net asset value (NAV), because selling stock priced higher than the underlying crypto allows the firm to accumulate more coins per share.
According to Goodwin, the sector has experienced significant compression, with valuations dropping from premiums down to NAV or lower. Business models reliant on premium-priced equity and debt are now under severe strain, leaving many treasury companies trading at or below NAV.
Furthermore, rising yields increase the returns investors demand on preferred shares and convertibles, widen the equity risk premium, and present a more attractive risk-free alternative. Each of these factors raises the hurdle for a financing framework that previously relied heavily on NAV premiums and cheap hybrid capital.
While individual company discounts also stem from specific crypto and corporate factors, broader yield trends establish the overarching market backdrop.
Treasury yields reach DeFi
A study published in 2026 by Finance Research Letters, which analyzed Aave data, established a link between stablecoin borrowing and deposit rates and US Treasury yields, noting that the 10-year yield displayed the most consistent explanatory power across different maturities.
Similarly, an ECB working paper focusing on Aave indicated that restrictive monetary shocks reduce both stablecoin borrowing demand and liquidity supply, with the transmission mechanism depending on the balance between arbitrage and leverage channels.
While these connections vary depending on the market and timeframe, individual decentralized finance (DeFi) rates ultimately respond to local supply and demand dynamics. Although Bitcoin’s spot price can absorb a Treasury shock for weeks, crypto dollar funding markets immediately feel the impact through rising borrowing costs.
During the era of zero interest rates, a 4% or 5% crypto yield looked appealing compared to cash returns near zero. However, with the 10-year Treasury yielding 5%, DeFi yields must account for smart contract, liquidity, counterparty, stablecoin, oracle, and governance risks. Consequently, DeFi products require higher returns, increased leverage, token incentives, or alternative liquidity structures to remain competitive.
Platforms like RWA.xyz currently list 108 tokenized US Treasury fund products, including USYC, USDY, BUIDL, and iBENJI. Meanwhile, the San Francisco Fed estimates that if recent growth trends continue, stablecoin issuers’ holdings of US Treasuries could roughly double to about $400 billion by 2030.
Where Bitcoin and its plumbing go from here
If the 10-year yield declines back below 5% as oil and inflation ease—and if adviser and brokerage allocations persist—Citi’s $113,000 price target will serve as the primary benchmark for institutional demand.
Under such conditions, premiums for treasury companies could return, basis trades would become more profitable, and the adoption of tokenized collateral would expand, aligning with Citi’s projection of a $5.5 trillion to $8.2 trillion tokenization market by 2030.
Conversely, if yields remain near 5% and real yields stay close to 3%, Bitcoin may continue to experience intermittent rallies, with every upcoming macroeconomic data shock increasing the probability of a liquidation flush.
Under this tighter monetary scenario, discounts on treasury companies would likely persist, preferred stock and debt financing would become more expensive, DeFi borrowing rates would increase, and low-risk DeFi yields would lose their attractiveness relative to tokenized Treasuries.
Ultimately, any disorderly movement in bond or oil markets would place the greatest strain on leveraged perpetual futures, crypto-backed loans, and the debt and preferred stock structures of treasury companies.
Ultimately, Bitcoin’s price successfully absorbed the bond market shock of the third quarter, while the underlying financial plumbing absorbed the subsequent repricing.
अक्सर पूछे जाने वाले प्रश्न
01How did high Treasury yields affect Bitcoin in the third quarter?
Despite US 10-year Treasury yields hitting 5.34%—their highest level since 2002—Bitcoin gained about 43% and Ethereum rose about 71% over the same three-month period, supported by strong ETF inflows and adviser allocations.
How have higher yields impacted Bitcoin leverage and financing?
Higher benchmark rates increased borrowing costs for explicit leverage and implicit mechanisms like perpetual futures and basis trades. This environment compressed the valuations of Bitcoin treasury companies down to or below their net asset value (NAV) and led to hundreds of millions in forced liquidations during macroeconomic shocks.
02Are Treasury yields connected to decentralized finance (DeFi) markets?
Yes. Studies examining Aave data have shown that stablecoin borrowing and deposit rates are linked to US Treasury yields, meaning restrictive monetary policies directly influence crypto dollar funding and borrowing costs.