ESMA गैर-अनुपालन वाले स्थिर सिक्कों (stablecoins) के लिए EU कस्टडी और ट्रांसफर सेवाओं को समाप्त करने का प्रस्ताव करता है
ESMA ने गैर-अनुपालन वाले स्थिर सिक्कों (stablecoins) के लिए कस्टडी और ट्रांसफर सेवाओं पर प्रतिबंध लगाने के लिए यूरोप के MiCA नियमों का विस्तार करने का प्रस्ताव दिया है, जो पिछली नीतियों से एक महत्वपूर्ण बदलाव को चिह्नित करता है जो डीलिस्टिंग के बाद बुनियादी भंडारण की अनुमति देती थीं।

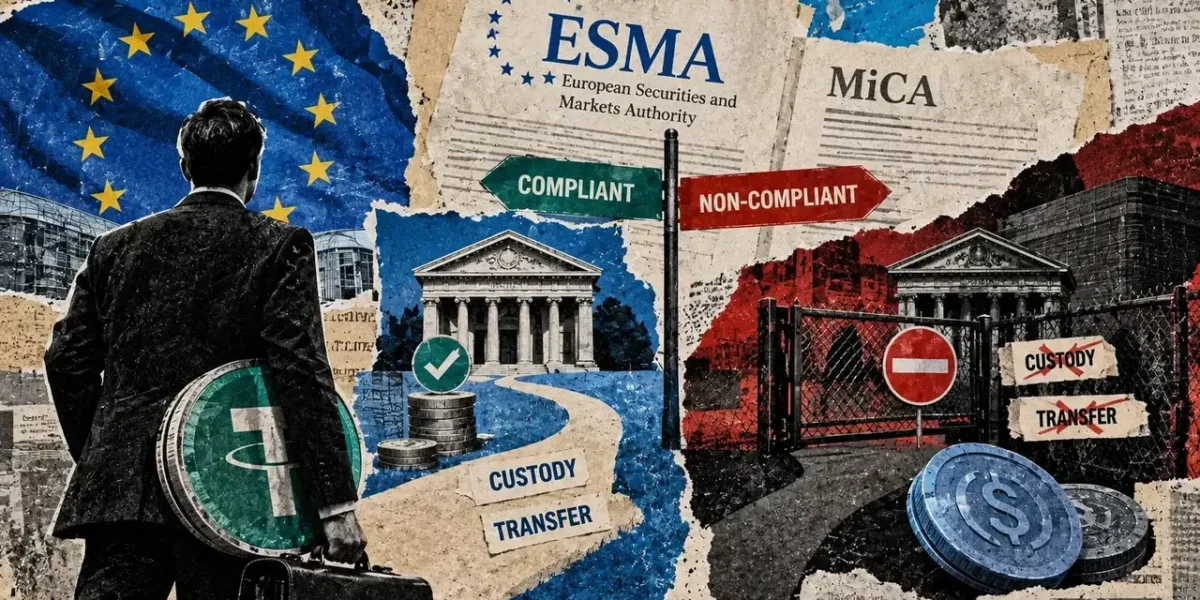
The European Securities and Markets Authority (ESMA) is seeking to expand Europe’s rules on non-compliant stablecoins. Rather than limiting restrictions strictly to trading, the watchdog wants to encompass the underlying services that enable customers to store and move these digital assets. If enacted as recommended, the adjustment would eliminate the option of maintaining such tokens with a regulated custodian after their trading pairs are removed.
In its September 30, 2026 response regarding a review of the EU’s Markets in Crypto-Assets regulation (MiCA), ESMA urged the European Commission to outlaw every licensable crypto-asset service involving stablecoins that fail to meet the regulation’s statutory guidelines. Custody operations and token transfers are both included on this restricted list. Consequently, this shift would impact both prospective buyers and existing holders who have already ceased trading.
This position marks an evolution from the regulator’s stance in January 2025, which maintained that basic custody and transfer capabilities should remain accessible. While this adjustment might afford compliant tokens a structural distribution advantage across Europe, the proposal does not inherently trigger a compulsory conversion timeline or a widespread global shift in demand.
The permission left after delisting
ESMA’s January 17, 2025 statement separated the act of offering non-compliant stablecoins to the public or listing them for trade from simply storing or transferring them. Platforms were directed to pull these tokens from trading rosters, and ancillary services had to terminate wherever they amounted to a public offer.
Under that prior transition phase, acquisition curbs were anticipated by late January 2025, alongside temporary sell-only functionalities running through the end of the quarter.
For investors, this distinction regarding custody was vital. Losing access to a trading pair did not automatically mean losing the infrastructure required to secure an existing balance or process its withdrawal. ESMA noted at the time that investors holding these assets could encounter degraded execution conditions, even while transfers and custody stayed open.
A historical parallel illustrates this framework. In reporting dated March 3, 2025, CryptoSlate highlighted Binance’s strategy to phase out nine tokens’ trading pairs for European Economic Area users by March 31, while continuing to support deposits, withdrawals, conversions, and custody. This reflected the exchange’s stated operational approach in March 2025.
The September submission would swap this activity-by-activity breakdown for a sweeping asset-compliance standard. ESMA contends that the absence of an explicit ban introduces imbalances between compliant and non-compliant issuers, thereby encouraging regulatory arbitrage.
The jurisdiction for this reach stems from MiCA’s Article 3 definitions. Custody encompasses safeguarding or overseeing clients’ crypto-assets or their access credentials, such as private keys. Transfers involve relocating assets on behalf of a client from one ledger address or user account to another. Both are explicitly designated services, with Article 82 imposing strict client-agreement rules on transfers.
Furthermore, provider licensing remains distinct from token-level compliance. Article 59 mandates authorization as a crypto-asset service provider—or qualifying permissions for specific financial entities—and dictates that authorizations must explicitly outline authorized services. A provider license alone does not determine whether an individual stablecoin is cleared for servicing.
Consequently, an existing holder could not bypass the suggested restriction simply by opting out of trading entirely. If the current text becomes law without specific exemptions, the custodian’s continued safekeeping activities would automatically fall under the prohibition.
ESMA’s response constitutes a policy recommendation rather than an official legislative amendment. The European Commission’s consultation window closed on September 30, and official notices indicate that the resulting review report may eventually accompany a formal legislative proposal, if deemed necessary.
Section 3.2 of ESMA’s submission omits any implementation timeline, withdrawal exemption, or wind-down procedure. This omission is critical, as dismantling custody services requires an established protocol for returning assets already managed by a provider, especially given that the proposed ban simultaneously captures transfer operations.
Current custody guidelines offer a framework for reference. Article 75 mandates protocols to return client crypto-assets or access credentials without delay. In addition, client assets must be strictly segregated from the provider’s proprietary holdings.
A clarification from the European Commission via ESMA, issued on February 18, 2026, further specifies that returned assets must match the exact type held when the client submits a withdrawal request. Although a provider may facilitate conversion into fiat or another crypto-asset, the client must explicitly request this at the time of withdrawal, and the provider must hold separate authorization for that additional service.
This pre-existing interpretation does not clarify how a blanket future service restriction would manage liquidations or exits. However, it clarifies why delisting, custody termination, and mandatory conversion cannot be treated as interchangeable outcomes. Policymakers would need to address how any fresh prohibition aligns with the statutory duty to return client assets.
The stablecoin proposal is aimed squarely at professional services. It does not unilaterally ban personal ownership, mandate asset freezes, or impose compulsory conversions. A holder’s capacity to retain an asset and a licensed entity’s legal ability to store or move it on that customer’s behalf represent entirely separate issues.
Trading shares do not measure custody exposure
Prior delisting events demonstrate how trading metrics can fluctuate on European-facing platforms without triggering a comparable transformation across the wider global market.
In a July 2026 paper, researchers Nicola Borri and Kirill Shakhnov analyzed trading activity for dollar-pegged tokens USDT and USDC across 14 centralized exchanges pulled from CoinMarketCap’s top 30 venues. Their daily pair-volume metrics, sourced from CryptoCompare, span from January 1, 2024, through December 7, 2025.
The study classifies Bitstamp, Coinbase, Gemini, and Kraken as “regulated-facing” because their Similarweb European Union audience shares exceed 10%; each of these platforms also maintains a U.S. audience share above 10%. The remaining 10 venues are categorized as globally focused, a group that includes Binance despite its EEA delisting actions. This audience proxy does not isolate individual EU-resident transactions, nor does it establish a clean separation of legal exposure.
Near the study’s April 1, 2025 event date, the authors calculated that USDC’s share of combined USDT and USDC trading volume increased by roughly six percentage points on regulated-facing exchanges compared to global venues. This estimate evaluates a 30-day window using smoothed, detrended data to measure relative trading shifts between exchange categories.
Additionally, the authors estimated that USDT trading volume dropped by about 20% on regulated-facing exchanges relative to global platforms, whereas the fluctuation in USDC volume was not statistically significant. USDC gained market share primarily because overall USDT trading contracted within that comparison, rather than through an observed expansion in absolute USDC trading volume.
Aggregate USDC-to-USDT trading volume ratios across the sample remained relatively flat around the event horizon. These figures reflect exchange turnover within the sample rather than worldwide demand or total EU custodial balances. Neither the legal documents nor the academic study provides a total figure for the assets that a future custody restriction could impact.
Should the proposal pass into law in its current iteration, compliant tokens would retain access to regulated custody and transfer pipelines, whereas non-compliant tokens would be cut off entirely. For users who rely on regulated providers to store and manage dollar-pegged balances, regulatory compliance could fundamentally alter the utility of a digital asset independently of whether a trading pair remains active.
The definitive text to watch will be any future legislative amendment, paying specific attention to its scope, enforcement timeline, and treatment of legacy balances. How lawmakers reconcile a termination of custody services with the obligation to return client assets will ultimately dictate whether and how current holders must exit regulated structures.
अक्सर पूछे जाने वाले प्रश्न
01What is ESMA proposing regarding non-compliant stablecoins in the EU?
ESMA is asking the European Commission to ban all licensable crypto-asset services—including custody and transfers—for stablecoins that fail to comply with the Markets in Crypto-Assets (MiCA) regulation.
02Does this proposal mean personal ownership of stablecoins is banned?
No. The proposal focuses entirely on professional financial services and does not ban personal ownership, freeze tokens, or force compulsory conversions.
03Are these changes final law?
No. ESMA’s response is a policy recommendation submitted during a consultation period. It requires formal legislative action by the European Commission to become enacted law.