New Treasury rules could change how stablecoin issuers get your dollars back
New Treasury rules from the SEC mandate central clearing for debt transactions, impacting how stablecoin issuers liquidate reserves into cash for customer redemptions and changing borrowing costs.

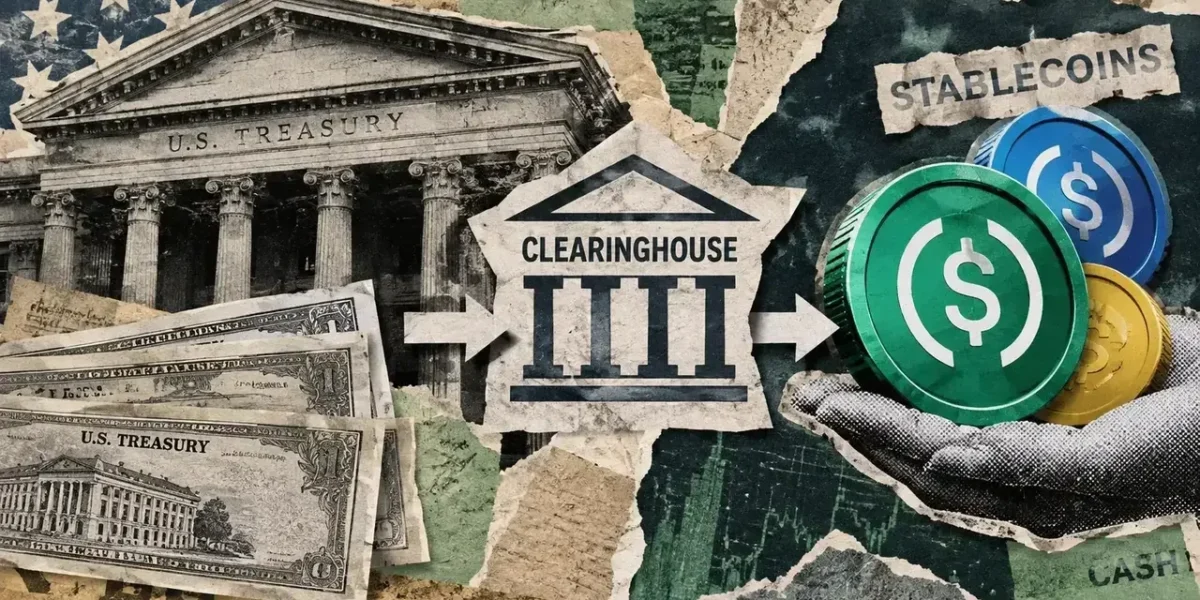
US government debt ranks among the most liquid assets globally to borrow against, enabling financial companies to raise cash without permanently parting with their investments.
Washington is currently overhauling the regulations governing this borrowing activity. Ultimately, these shifts will impact the cryptocurrency sector through the firms that maintain Treasury securities as backing for their dollar-pegged tokens.
The Securities and Exchange Commission (SEC) wants a greater volume of Treasury transactions to route through a central clearinghouse—an entity that acts as the universal buyer to every seller and the universal seller to every buyer.
Under this framework, if a single trading firm defaults, the surviving counterparty can rely on the clearinghouse to fulfill the transaction according to its established protocols, rather than attempting to recover funds directly from the insolvent enterprise.
Because offering such robust safeguards requires substantial financial backing, the new system will inevitably influence what companies pay to execute trades and secure loans. Stablecoin issuers rely heavily on these financial services when they must liquidate reserve assets into cash to fulfill customer redemptions. Consequently, the cost and accessibility of Treasury trading directly dictate how efficiently their tokens function.
The SEC has established a compliance deadline of December 31 for eligible outright purchases and sales of Treasuries, followed by June 30, 2027, for eligible repurchase agreements, commonly referred to as repos. On September 22, Commissioner Mark Uyeda indicated that the agency does not currently plan to grant extensions.
These new mandates apply to specific trades involving clearing members rather than every retail purchase of a Treasury bond.
Owning the Treasury bond is only half the transaction
Consider an investment fund that holds Treasury securities but requires immediate cash before the federal government matures the debt. The fund has two options: it can permanently sell a portion of those holdings, or it can execute a repo. In a repo, the fund sells the securities immediately with a binding agreement to repurchase them on a specific future date—frequently the next day—at a slightly elevated price.
From an economic perspective, the fund has effectively taken out a cash loan. The Treasuries act as collateral protecting the lender, while the price differential serves as the interest. The borrower gains immediate liquidity while maintaining a pathway to reclaim its securities, and the lender earns a yield on otherwise idle capital.
Dealers, which are typically major banks or securities firms, facilitate a vast portion of this marketplace. Explanations of the repo market from the New York Fed trace cash flows from institutional lenders like money-market funds, through dealers, to borrowers such as hedge funds.
Dealers routinely borrow in one segment of the market and lend in another, profiting from the spread while arranging and financing the trades.
The sheer magnitude of this activity is staggering. According to Federal Research, transaction volumes used to calculate the Secured Overnight Financing Rate (SOFR) expanded from roughly $1 trillion in early 2022 to approximately $3 trillion.
SOFR tracks the expense of overnight borrowing collateralized by Treasuries, with these volumes capturing the underlying transactions that feed the benchmark rather than the entire repo ecosystem.
Despite trillions of dollars changing hands, individual market participants can still find it difficult to secure favorable borrowing terms. Dealers face strict internal and regulatory caps on their business volume, as their trades consume valuable capital and count against regulatory thresholds.
An abundance of available cash elsewhere in the financial system offers little help if the intermediary connecting you to those funds has already hit its capacity limit.
Central clearing can alleviate some of this pressure via netting—a process that recognizes and combines offsetting financial obligations. To take a simplified example, if a dealer owes $100 while simultaneously expecting to receive $95 on the identical settlement date:
If both liabilities qualify for netting through a single clearinghouse, the requisite cash transfer shrinks to just $5.
Real-world Treasury transactions also require the physical delivery of securities, and complex legal agreements dictate which obligations can be successfully combined. Nevertheless, the fundamental advantage remains straightforward: companies require less total capital to settle offsetting trades, and qualifying netting arrangements can decrease the balance-sheet resources those positions consume.
This efficiency could empower a dealer to service a greater number of clients using its existing resource pool. Whether these savings translate into cheaper borrowing costs for end-users depends on how much capital the dealer saves and how much of that windfall it decides to pass along after factoring in clearing expenses.
Someone still has to bring the collateral
A clearinghouse is able to guarantee trade completion because it amasses robust financial buffers and maintains strict protocols for managing defaulting members. International standards dictate that clearing institutions must actively monitor their risk exposures and hold adequate resources to absorb market stress.
A cornerstone of this risk mitigation is margin—comprising cash or eligible securities pledged against an open position. If a firm defaults and liquidating its portfolio incurs a loss, this collateral absorbs the financial blow.
Until that time, the participating company must keep those assets locked up and ready, even if it would rather deploy the capital elsewhere.
This dynamic illustrates how a risk-reduced transaction can simultaneously impose heavier operational demands on its participants. Being financially capable of supporting a trade over its lifespan does not guarantee a firm will have the correct collateral prepared on demand, particularly when multiple obligations require concurrent funding.
Furthermore, numerous market participants require an intermediary to gain entry into the infrastructure. The Fixed Income Clearing Corporation (FICC) operates a Sponsored Service model, wherein an approved sponsoring member manages operational tasks and guarantees specific obligations on behalf of its clients.
Such sponsors assume significant operational workloads and financial risks, which directly influences the pricing and terms they extend to customers.
Conversely, the FICC’s Collateral-in-Lieu program for eligible cash lenders employs protective mechanisms leveraging the transaction’s existing Treasury collateral, sparing those lenders from posting initial margin under that specific framework. This setup demonstrates why mandatory clearinghouse participation does not automatically mean every entity must scramble for the exact same amount of incremental cash.
Customers must still evaluate the total cost of access, which includes provider fees alongside the opportunity cost of immobilizing collateral.
While clearing-induced netting savings can make certain legs of a transaction more affordable, new compliance services may introduce expenses elsewhere. Consequently, the final financial tally depends entirely on the specific arrangement a client can negotiate.
A DTCC survey of FICC members conducted in July highlights why careful selection of providers is critical. Although 79% of responding netting members reported having the requisite account infrastructure already in place, only about one-third anticipated offering Treasury cash clearing services to external clients.
While these statistics reflect only the surveyed group and do not guarantee that clients will face total exclusion, they underscore an important market reality: a dealer’s technical readiness to comply with rules is not synonymous with a willingness to accept your specific business.
If borrowers have a limited selection of providers, those service providers face less competitive pressure to pass along the cost savings generated by central clearing.
Digital dollars inherit the operating hours
Issuers of dollar-pegged stablecoins often maintain a portion of their reserve backing in short-term Treasuries because these assets generate yield and boast deep secondary resale markets. However, when an eligible token holder requests a redemption, the issuer is obligated to pay out true dollars, necessitating readily available cash or a dependable mechanism to liquidate reserves rapidly.
This operational reality differs fundamentally from traditional banking, where a legacy deposit sits natively on a blockchain network. Tokenized deposits and the underlying mechanisms of traditional bank lending explain how those products preserve a customer’s direct claim against a banking institution.
For a Treasury-backed stablecoin, an issuer’s underlying reserve management policies and banking partnerships dictate whether it can consistently meet its published redemption guarantees.
The connection to central clearing operates through these very relationships, regardless of whether the stablecoin issuer trades directly or utilizes external fund managers and intermediaries.
If an issuer’s service providers can buy, sell, or finance Treasuries with greater efficiency, managing redemptions could become smoother and more cost-effective. Should market access grow more expensive, however, the issuer may confront rising reserve-management overhead—though that does not automatically translate to a direct fee for end-users.
Moreover, central clearing does not transform the reserve market into a 24/7/365 operation. A user can transfer a token on a Sunday while the issuer’s partner banks and securities clearing networks operate on standard banking hours. Furthermore, moving a token peer-to-peer is entirely distinct from instructing an issuer to wire fiat currency into a traditional bank account.
Issuers must proactively bridge this operational gap by maintaining appropriate cash buffers and establishing clear redemption terms.
Holding higher volumes of cash ensures withdrawal demands can be met swiftly, but cash typically yields lower returns than other permitted reserve assets. Conversely, leaning heavily on the sale or financing of securities preserves yield flexibility, but it makes reliable access to clearing and repo markets paramount.
Every issuer must carefully design an operating model that functions reliably when customers demand their capital back.
This sweeping regulatory overhaul could enhance market access by maximizing dealer efficiency and establishing standardized protocols for managing corporate defaults. Alternatively, it risks leaving certain participants dependent on a concentrated pool of providers, particularly if onboarding with a replacement account proves time-consuming.
Both scenarios can easily coexist within the same financial ecosystem, with large-scale institutional clients securing vastly superior terms compared to smaller operators.
As the implementation deadlines loom, monitoring access pricing and provider-switching capabilities remains essential.
Treasury-backed tokens ultimately rely on intermediaries capable of converting securities into fiat payments. The intended benefits of Washington’s updated regulatory framework will only reach tokenholders if this conversion process becomes more dependable at a cost stablecoin issuers can sustainably absorb.
Frequently Asked Questions
01What are the new Treasury rules and who do they affect?
The SEC is requiring more Treasury transactions to pass through central clearinghouses. While it does not apply to every individual Treasury purchase, it directly impacts clearing members, financial institutions, and stablecoin issuers that rely on Treasury securities to back their dollar-pegged tokens.
02When do the SEC clearing deadlines take effect?
The deadlines are set for December 31 for eligible outright purchases and sales of Treasuries, and June 30, 2027, for eligible repurchase agreements (repos).
03How do these rules impact stablecoin holders?
Stablecoin issuers keep reserves in short-term Treasuries. If new rules alter the cost and availability of trading or financing those Treasuries, it could impact how efficiently issuers manage redemptions and handle customer withdrawals.
04Does central clearing mean the Treasury market operates 24/7?
No. Central clearing does not make the underlying reserve market operate around the clock, meaning issuers must still carefully manage cash buffers to handle redemptions outside of standard banking hours.