Lido’s proposed staking route needs over 13 times the default entry bond
Lido proposes a new Community Staking Module requiring a 32 ETH entry bond for larger Ethereum validators, aiming for mainnet rollout in Q4 2026 while offering higher capital efficiency at scale.

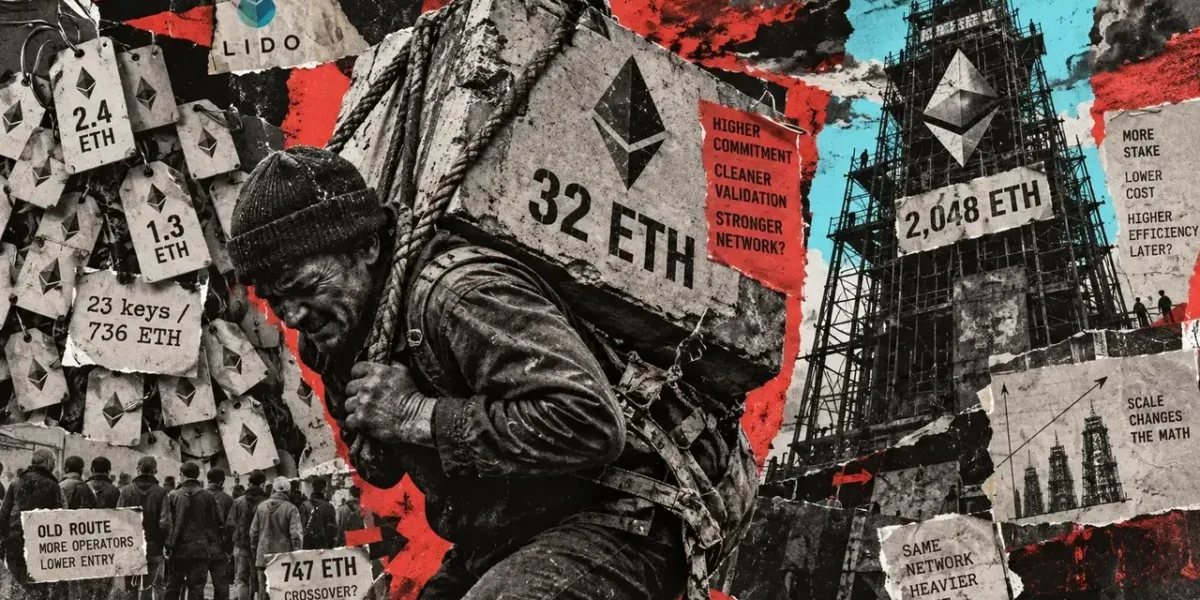
Lido’s proposed setup for running larger Ethereum validators calls for a 32 ETH entry bond, compared to 2.4 ETH for its current default pathway. While this higher collateral level can become more capital-efficient once sufficient stake is assigned to the validator, an operator’s specific profile and position in the funding queue dictate how beneficial that advantage actually is.
The deployment plan published in October details the Community Staking Module 0x02, a distinct module for permissionless operators that will run alongside the existing 0x01 route. It aims to support compounding validators carrying up to 2,048 ETH of effective stake, a significant jump from the 32 ETH limit on current-route validators. Every individual validator is identified by a unique key.
This path remains active on the Hoodi testnet, with mainnet rollout anticipated in Q4 2026. The deployment documentation addresses preparations for mainnet and indicates that the module’s Staking Router parameters will face a subsequent vote. Milestones achieved thus far include the July 20 approval of the launch proposal and the September 1 testnet announcement, rather than a full mainnet activation.
When evaluated as operator fees per ETH bonded, the new structure achieves parity with an initial default key at approximately 747 ETH under conditions of equal yield and performance. However, if an operator decides to spread a 32 ETH budget across multiple existing default keys, that modeled threshold climbs to roughly 1,330 ETH. These figures represent fee-efficiency comparisons calculated prior to accounting for operational costs, penalties, and funding delays.
The proposed collateral requirement sits at 32 ETH for the first key and 30 ETH for each subsequent key. By comparison, under Lido’s current 0x01 default profile, those figures are 2.4 ETH and 1.3 ETH, respectively.
It is important to distinguish between collateral and stake. The bond acts as the operator’s security deposit, maintained as stETH to absorb potential losses and charges. Meanwhile, the protocol provides the validator’s stake independently. Submitting a 32 ETH bond does not equate to purchasing the validator’s delegated ETH or securing a guaranteed allocation.
Ethereum’s EIP-7251 enables validators utilizing 0x02 withdrawal credentials to compound, establishing a maximum effective balance of 2,048 ETH while preserving 32 ETH as the minimum activation balance. Lido’s bond curve adjusts according to the number of keys, meaning an existing 0x02 key requires no extra collateral as its underlying stake expands.
At maximum balance, the initial key’s bond represents 1.5625% of the delegated stake, translating to 0.5 ETH of collateral per 32 ETH operated. The ratio for subsequent keys is roughly 1.465%. These proportions only apply to a fully funded validator; a key functioning with merely its initial stake bears a substantially heavier collateral burden.
Operators are slated to receive a 2% share of staking rewards, with the remaining 8% directed to the treasury. The deployment setting that grants operators 100% of the module fee ensures they collect that entire 2% portion. This allocation functions neither as a 2% staking APR nor as a claim on all rewards generated by the validator.
Why 747 ETH is only the first comparison
Calculations from CryptoSlate maintain equal gross staking yield, qualifying performance, and operating duration across models. Portfolios on the existing route are presumed to be fully funded and eligible for fees throughout the entirety of the comparison timeframe. These assessments pit operator fees against one another before factoring in infrastructure expenses, gas fees, penalties, and the bond’s own stETH yields.
Representing gross staking yield over the comparison period as $y$ and effective stake as $S$, the proposed first-key fee income per ETH bonded is calculated as $0.02 times S times y div 32$. Conversely, the existing first default key yields $0.035 times 32 times y div 2.4$. Setting these equations equal yields 746.67 ETH, or roughly 747 ETH.
The 747 ETH metric evaluates first-key fees per ETH of collateral utilizing varying levels of operator capital, presuming that both validators remain funded and fee-eligible for identical durations.
Alternatively, a 32 ETH budget can finance the bonds for 23 existing default keys, utilizing 31 ETH for bonds and covering 736 ETH of delegated stake provided every key receives funding. A single key on the proposed route equals that portfolio’s aggregate operator fees at 1,288 ETH, and matches fees per ETH actually bonded at approximately 1,330 ETH because the existing portfolio only locks up 31 ETH.
Verified profiles shift these outcomes. Lido’s operator economics matrix assigns Independent Community Stakers (ICS) a 1.5 ETH initial bond followed by 1.3 ETH for additional keys, paired with a 6% reward share for their first 16 keys and 3.5% thereafter. Verified independent clusters leveraging distributed validator technology (IDVTC) require a 1.5 ETH initial bond and 0.5 ETH subsequently, collecting 3.5% on their first 64 keys and 2% after that. Such profiles demand specific eligibility, whereas the proposed module features a single permissionless profile.
| Existing-route profile | Keys and bond within a 32 ETH budget | Fully funded existing stake | New first-key stake for equal fees per ETH bonded |
|---|---|---|---|
| Default | 23 keys; 31 ETH | 736 ETH | About 1,330 ETH |
| Verified ICS | 24 keys; 31.4 ETH | 768 ETH | About 2,022 ETH |
| Verified IDVTC cluster | 62 keys; 32 ETH | 1,984 ETH | 3,472 ETH, above the 2,048 ETH ceiling |
The table divides fees by the required bond amount actually posted. Default and ICS portfolios leave 1 ETH and 0.6 ETH unallocated. Distributing both alternatives across the identical 32 ETH budget results in total-fee crossover points of 1,288 ETH and 1,984 ETH, respectively. Returns generated from leftover capital fall outside the scope of this fee-centric model.
Consequently, the ICS portfolio leaves minimal breathing room below the proposed validator ceiling to secure a fee-efficiency edge. The modeled DVT cluster maintains its lead throughout the accessible balance range. Neither outcome guarantees net profitability, given that operational setups incur varying overhead costs.
Additional keys necessitate separate evaluation. At the margin, comparing a proposed 30 ETH bond against an existing default 1.3 ETH bond produces a theoretical fee-efficiency crossover near 1,292 ETH, differing from the initial first-key figure of 747 ETH.
Funding and penalties determine the net result
The October roadmap outlines a 16-position top-up queue. A key initially acquires its starting 32 ETH via the deposit queue before transitioning into a separate first-in, first-out queue for supplementary funding.
In accordance with Lido’s queue mechanics, top-ups service the front of the line in multiples of 2 ETH, constrained by accessible stake. A partially funded key stays at the head until its capacity is completely met. Subsequent keys are blocked from bypassing it for top-ups, and a congested queue restricts fresh initial deposits.
The proposed cap for the module is set at 2% of total Lido stake. This restriction limits module allocation rather than promising any single operator a fully funded validator.
Such mechanics transform a straightforward balance comparison into a question of timing. An operator that ultimately attains 2,048 ETH might spend a significant portion of the comparison period idling or operating on a reduced balance. The most pertinent metric is the average reward-eligible effective stake maintained throughout that timeframe. Because current-route keys likewise demand funding and activation, the fully funded portfolios outlined in the table serve as conditional benchmarks.
While compounding assists balance growth, the module proposal itself ties capital efficiency directly to prevailing effective balances, module capacity, and protocol inflows. Calculating potential outcomes at maximum capacity fails to reveal how rapidly an operator will scale to reach it.
Lido’s reward framework isolates operator fees from the stETH rebasing earned on collateral. Factoring bond returns back in alters any total-income comparison. Evaluating returns per ETH bonded mandates utilizing identical bond-return rates and durations before that income stream can neutralize differences between alternatives.
Performance metrics also dictate payouts. A validator operating under the required threshold forfeits operator rewards for that specific frame, though its underlying bond can keep rebasing. Any depleted collateral must be replenished before rewards become claimable.
The proposed configuration relies on a 28-day frame, a 3% performance buffer, and a three-strike threshold featuring a six-frame strike lifespan. Balance-scaled penalties can escalate to 16.512 ETH for ejections tied to poor performance and 6.4 ETH for delayed exits at a maximum 2,048 ETH balance. Charges for exit delays adhere to a four-day deadline and are settled post-withdrawal.
A comprehensive net comparison must incorporate bond returns while subtracting infrastructure outlays, gas expenditures, and assessed penalties, factoring in true funded durations and reward eligibility. While running fewer keys might alter operational expenses, the parameters alone cannot price out that variance.
Prior to mainnet deployment and the module-specific router vote, key indicators to monitor include final fee structures, cap configurations, accessible funding, and progression rates through the queue. The proposed pathway presents default operators with a conditional route toward enhanced fee efficiency at scale; however, verified operators maintain stronger existing alternatives, and the lower-bond 0x01 route will continue to operate concurrently.
Frequently Asked Questions
- What is Lido’s Community Staking Module 0x02? It is a proposed permissionless staking module designed to run larger Ethereum validators supporting compounding stakes up to 2,048 ETH.
- How much bond is required for the new staking route? The proposed route requires a 32 ETH entry bond for the first key and 30 ETH for each subsequent key.
- When is the new staking module expected to launch on mainnet? Mainnet deployment for the Community Staking Module 0x02 is anticipated in Q4 2026.
- Do operator fees guarantee total validator profitability? No, fee-efficiency comparisons do not account for infrastructure expenses, gas costs, penalties, or net profitability.