Metaplanet ने क्रेडिट-रेटिंग बोली में 10,000 बिटकॉइन बेचे, और बाद में प्रति सिक्का अधिक कीमत पर 11,000 BTC वापस खरीद लिए
मेटाप्लानेट (Metaplanet) ने अपने कर्ज को चुकाने और अपनी क्रेडिट प्रोफाइल में सुधार करने के लिए 10,000 बिटकॉइन बेचे, और बाद में एक नई यील्ड रणनीति के हिस्से के रूप में तीसरी तिमाही के दौरान अधिक कीमत पर 11,000 बीटीसी (BTC) को वापस खरीद लिया।

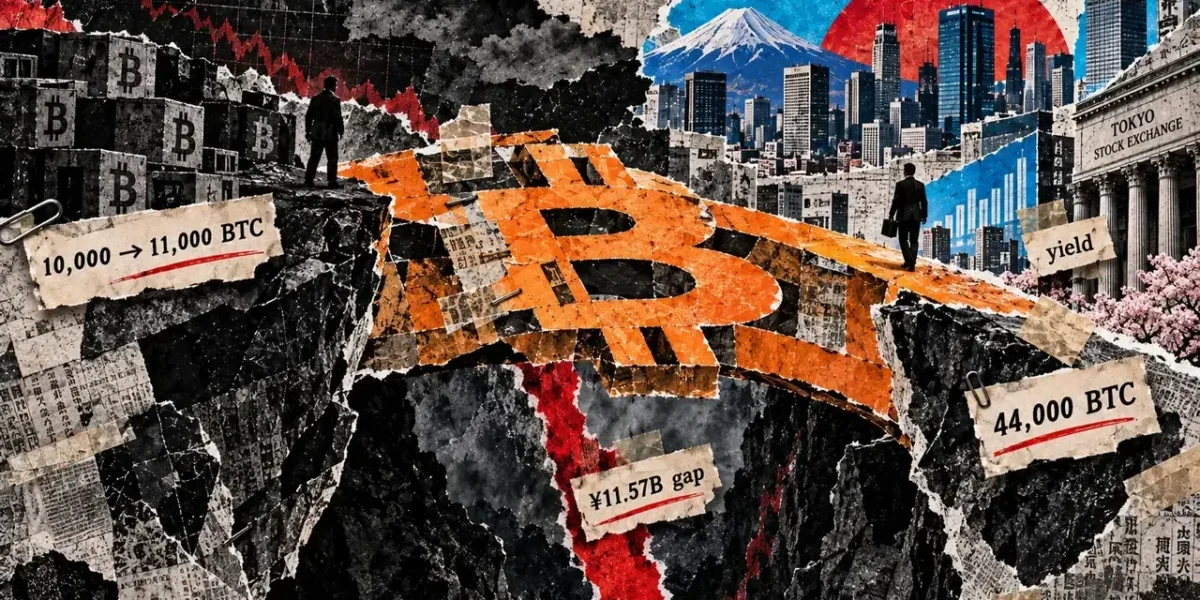
In an effort to bolster its credit profile and move past pure accumulation during the third quarter, Metaplanet sold 10,000 Bitcoin and subsequently bought back 11,000 BTC.
The Tokyo-listed enterprise reported converting a sufficient amount of Bitcoin into cash throughout the third period to surpass the total outstanding principal of its borrowings, bonds, and other interest-bearing debt. Afterward, the firm replenished the stash at a higher rate per coin, closing out Sept. 30 with 44,000 BTC, marking a net increase of 1,000 for the quarter.
This maneuver constitutes part of a broader push to convince fixed-income investors and rating agencies that Metaplanet’s Bitcoin holdings can successfully be monetized as obligations fall due.
The business intends to pursue a credit rating, leveraging a sturdier financial framework to fuel a new initiative that borrows via preferred stock, bonds, and Bitcoin-backed facilities prior to allocating capital into higher-yielding assets.
The liquidity demonstration came at a price
Because Bitcoin appreciated between Metaplanet’s initial sale and its later repurchase, the company ended up paying notably more to reconstruct the liquidated position.
Based on preliminary, unaudited metrics from its report, Metaplanet offloaded 10,000 BTC for an average of ¥12.47 million per coin, raking in ¥124.7 billion. It later acquired 11,000 BTC at an average of ¥13.63 million each, outlaying ¥149.9 billion.
The roughly ¥1.16 million gap between disposal and acquisition pricing points to an adverse price delta of about ¥11.57 billion on the 10,000 coins required to restore the original stack. Metaplanet attributed this higher reacquisition cost to Bitcoin’s upward movement between the two events.
Management noted that these actions were carried out independently rather than as a single simultaneous swap. By selling the Bitcoin first, keeping the proceeds in cash, and repurchasing later, the sequence was designed to prove that reserves could genuinely be converted to cash instead of merely relying on theoretical market liquidity.
That distinction sits at the core of Metaplanet’s foray into credit markets. The firm explained that fixed-income participants and rating agencies might discount the liquidity value of Bitcoin if an issuer shows reluctance to sell when demands arise. Through the Q3 actions, Metaplanet aims to show creditors that its long-term accumulation strategy does not deter leadership from cashing out Bitcoin to fulfill financial duties.
Additionally, the sale generated a US capital-loss carryforward. Metaplanet calculates that subsidiaries under its US holding company could claim a deferred tax asset near $97 million, which may help offset future capital gains. This projection remains contingent upon closing steps and auditor evaluations, with the corporation noting that the asset could ultimately shrink or fail to be recognized altogether.
Should the deferred tax asset be officially recognized, Metaplanet noted that the tax treatment might absorb some or all of the impact stemming from transaction costs and the price gap between the sale and buyback.
Metaplanet wants to turn cheaper funding into recurring income
The organization plans to channel any enhanced credit access toward more than just financing additional Bitcoin acquisitions.
Under its newly revealed Net Interest Income Strategy, the company hopes to secure capital through instruments such as corporate bonds termed BitBonds, perpetual preferred stock, and Bitcoin-collateralized credit lines. Metaplanet would then deploy those funds into assets generating yields surpassing its total financing expenses, pocketing the difference as net interest income.
Among its primary investment targets are preferred securities issued by similar issuers and Bitcoin treasury companies. Such investments will be housed inside a strategic allocation expected to account for roughly 10% to 15% of total assets, while Bitcoin will maintain its status at about 85% to 90%.
Such a shift would transform Metaplanet closer to a financial intermediary within the expanding Bitcoin treasury ecosystem. Rather than depending primarily on equity issuance and appreciating Bitcoin reserves, the enterprise seeks to acquire funds at a specific cost, deploy them at a superior yield, and recycle the resulting cash flow into dividend payouts for preferred shares, debt service, and more Bitcoin purchases.
Japan is viewed by Metaplanet as a prime avenue for securing this funding edge. The company stated that yen-denominated financing typically incurs lower interest rates than dollar-based funding, while Metaplanet Securities provides direct outreach to domestic Japanese investors hunting for Bitcoin-linked yield instruments.
Furthermore, the firm anticipates that its pending investment in Super League Enterprise will broaden its reach into US capital markets, giving it the flexibility to choose between financing structures, maturities, and jurisdictions depending on prevailing market conditions. This transaction has not yet been finalized and remains subject to shareholder approval and regulatory protocols.
Metaplanet’s new income strategy keeps Bitcoin risk close
Even with efforts to diversify its revenue streams, much of Metaplanet’s balance sheet remains vulnerable to the exact same underlying asset.
The firm concedes that securities issued by other Bitcoin treasury entities can fluctuate alongside Bitcoin, thereby introducing a correlation between its core reserves and investments meant to yield recurring income. Metaplanet emphasized that issuer concentration, credit, leverage, and currency risks will be overseen within limits sanctioned by its board.
Its updated capital policy also differentiates between debt taken on to buy Bitcoin and leverage utilized for strategic investments. Bitcoin-linked borrowings are generally capped below roughly 10% of BTC net asset value, whereas financing tied to the strategic investment portfolio will be regulated independently via an asset-liability framework.
Metaplanet anticipates the fresh net interest income strategy will have a negligible impact on its 2026 consolidated performance, rendering the credit-rating push and future borrowing conditions the more pressing short-term benchmarks. The company has cautioned that it holds no guarantees regarding securing a rating, the specific tier it might achieve, or its ability to issue preferred shares and bonds on desired terms.
Consequently, the subsequent phase hinges on whether creditors validate Metaplanet for demonstrating a willingness to sell Bitcoin when called upon. A reduced cost of capital would afford the firm breathing room to scale its spread strategy; without it, borrowing to snap up yield-bearing, Bitcoin-linked securities becomes a significantly tighter economic balancing act.
अक्सर पूछे जाने वाले प्रश्न
01Why did Metaplanet sell and then buy back Bitcoin?
The company wanted to demonstrate to rating agencies and fixed-income investors that its Bitcoin reserves can be successfully monetized into cash to meet financial obligations, rather than just relying on theoretical market liquidity.
02Did Metaplanet profit from the sale and repurchase?
No. Because Bitcoin’s price rose between the two transactions, Metaplanet sold 10,000 BTC at a lower average price than it paid to repurchase 11,000 BTC later, resulting in an adverse price differential.
03What is Metaplanet’s Net Interest Income Strategy?
It is a new initiative to raise capital through instruments like corporate BitBonds, perpetual preferred stock, and Bitcoin-backed facilities, and then invest that money into assets that yield higher returns than the company’s financing costs.
04What role does Japan play in Metaplanet’s strategy?
Japan offers lower interest rates for yen-denominated financing compared to dollar funding, and Metaplanet Securities offers direct distribution to local investors seeking Bitcoin-linked yield products.