PropAMMs lower Solana trade costs, and public pool returns crash
A recent study highlights a market divide on Solana, showing that propAMMs offer superior swap prices for traders while passive pool depositors remain vulnerable to exploiting outdated quotes.

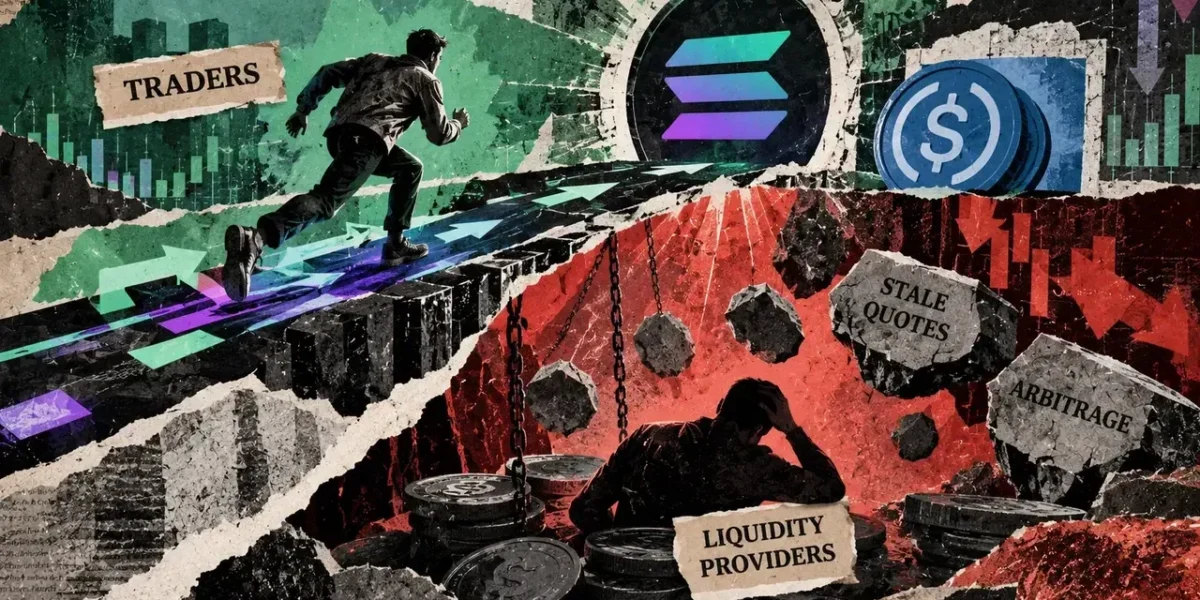
A recent preprint published on Sept. 29 highlights a clear market divide: traders can secure superior Solana (SOL) swap prices, while passive pool depositors remain vulnerable to traders exploiting outdated quotes.
When looking at quiet-market SOL/USDC fills, propAMMs—pools managed by professional operators—recorded a reference-relative execution cost proxy of 0.26 basis points. In contrast, public automated market makers (AMMs) registered 2.59 basis points.
Spanning from Sept. 1, 2025, through Aug. 31, 2026, the study also includes shorter data samples for Base and Monad. Fills are weighted by notional against Bybit’s size-weighted top-of-book USDT microprice, converted via its USDC/USDT midpoint. The authors list affiliations with ETH Zurich and Category Labs.
While swappers desire more tokens for the same input amount, liquidity depositors supply the inventory that others trade against and require adequate compensation for the accompanying risks. Lower execution costs benefit the former participant, but do not automatically create a sound investment case for the latter.
Swap prices and depositor returns on Solana
Across the Solana dataset, the paper notes two-second gross maker markouts of +0.37 basis points for propAMMs and −0.22 basis points for public AMMs. A markout evaluates a fill against a subsequent reference price, where a positive value favors the market maker.
Quiet-flow execution measures how much value a trader sacrifices compared to a relatively stable reference point. This proxy requires the reference price to move less than 1 basis point during the window from five seconds before to one second after a fill.
Conversely, maker markouts analyze the trajectory of a trade’s value after the pool accepts it. Combining these two distinct metrics would conflate pricing mechanics and adverse selection into a profitability claim that the underlying data cannot support.
If an external market shifts first, a pool continuing to display an obsolete price risks selling assets too cheaply or buying them too dearly. An arbitrageur steps in to realign prices, executing the correction directly against the liquidity already resting inside the pool.
Research on loss-versus-rebalancing views this arbitrage cost as just one factor within liquidity provider (LP) economics. Because total returns also depend on asset exposure and earned fees, any thorough investment assessment must factor in a specific position, holding period, and all corresponding income and expenses.
Trading fees require precise allocation, alongside inventory adjustments, hedging strategies, operating overhead, and transaction costs. The short-term horizon leaves this accounting incomplete, and broader venue averages cannot prove that professional pools directly drove aggregate passive-LP losses.
Depositors require a comprehensive return evaluation that takes the broader balance sheet into account, even as swappers benefit from liquidity whose operators actively manage pricing risks.
An April publication from Jump Crypto outlines how propAMMs—including its own BisonFi implementation—adjust pricing and available liquidity based on inventory levels, quote freshness, and incoming flow quality. Jump is an interested market operator, and individual implementations vary.
A market maker holding an oversized inventory of a specific asset can discourage incoming trades that add more of it, whereas stale pricing may warrant withdrawing depth or widening fee spreads. Similarly, routing paths linked to adverse selection might receive different terms than order flow deemed less risky by the maker.
From an economic standpoint, these controls enable makers to quote tighter spreads when anticipating lower risk. Forcing every counterparty onto identical terms would eliminate one of the primary methods used to evaluate and manage that risk. Ultimately, the price received by an ordinary swapper still needs independent measurement.
Documentation surrounding Jupiter’s AMM integration highlights a dedicated signer that identifies trades originating directly from its frontend, categorizing that specific flow as retail and non-toxic. Nevertheless, identifying the origin of a trade is distinct from independently proving that every single transaction is entirely harmless to the market maker.
Private market-making strategies frequently operate behind public settlement layers. While the capacity to defend a price helps a firm offer cheaper liquidity, actual access to that price hinges on the specific route and counterparty involved.
Quote reliability is a separate test
For Tessera on Base, execution averaged 1.08 basis points worse per trade—and 0.56 basis points worse by volume—than reconstructed previous-block-end quotes. Researchers categorize this block-timed fee phenomenon as “spoofing.”
Because the researchers contrast reconstructed pool outputs against actual execution while leaving individual screen quotes out of the measurement, the observed patterns offer no direct proof of operator intent. Consequently, better execution relative to a market reference can coexist with worse execution relative to an earlier quote.
In a March 20 report, routing provider 0x discussed how Base prices degraded between quote selection and ultimate settlement due to block timing shifts and changing spreads. Because the report did not name specific operators, it could not explicitly identify Tessera as the subject. Furthermore, 0x noted a policy of cutting off liquidity sources until any execution discrepancies are resolved.
When an advertised price attracts an order but a different execution price is ultimately delivered, rewarding the venue based purely on the advertised figure can misallocate volume. The fundamental question is whether routers consistently compare what a trader actually receives under the specific conditions of that transaction.
Jump has argued that routing engines capable of selecting executable prices dynamically during transaction execution can largely eliminate the gap between display and fill. The primary design takeaway is that a market maker can maintain its inventory, quote freshness, and counterparty safeguards, provided routers compare outputs that already incorporate those parameters.
Jupiter’s current Swap API documentation outlines competition among routing engines alongside a mechanism designed to sideline underperforming sources. Its integration guide also mandates quote-to-execution parity tests evaluated against identical pool snapshots.
While a parity check verifies agreement on a single snapshot, maintaining that consistency through subsequent updates remains a separate challenge. Competition among routing engines also leaves open whether each individual venue is actively reassessed during an executing transaction.
Although comparing executable outputs points toward a constructive design framework, its real-world effectiveness requires empirical measurement.
For any valid comparison, the executable output must reflect identical parameters, including trade size, caller, current pool state, and applicable charges. Otherwise, a favorable price available down one routing path could easily be mistaken for a price accessible to another.
Jupiter documents a platform swap fee on its Meta-Aggregator pathway compared to none on its Router pathway, and integrator fees along with landing arrangements can vary significantly. A protocol-level spread cannot substitute for the net amount ultimately received after accounting for all applicable charges.
Future evidentiary progress will require comparing quoted versus delivered outputs across matched transactions, clarifying which specific costs are included, and demonstrating how routing systems handle persistently underperforming sources.
Ultimately, passive liquidity demands a dedicated, position-level return assessment. Enhanced routing mechanisms can optimize the swapper’s decision-making process while leaving the depositor’s core investment questions completely unaddressed.
Frequently Asked Questions
01What is a propAMM?
A propAMM is an automated market maker pool controlled and managed by professional operators who can dynamically adapt pricing, liquidity depth, and risk controls.
02Why do public AMM depositors face risks?
Passive pool depositors remain exposed to arbitrageurs and informed traders who can pick off stale quotes when external markets move faster than the pool’s price updates.
03What is “spoofing” in the context of block-timed fees?
Researchers use the term to describe instances where execution outcomes lag or differ from reconstructed previous-block-end quotes due to block timing and spread changes.
04Does better routing solve passive LP losses?
No. While improved routing enhances the swapper’s experience and execution prices, it leaves the separate investment returns and risk assessments of passive liquidity providers unresolved.