Why an $88 billion bank reserve drop doesn’t prove a Bitcoin liquidity squeeze – yet
An analysis of Federal Reserve data reveals that a recent $88 billion drop in bank reserves does not prove a Bitcoin liquidity squeeze, as different reserve metrics and timeframes create conflicting market signals.

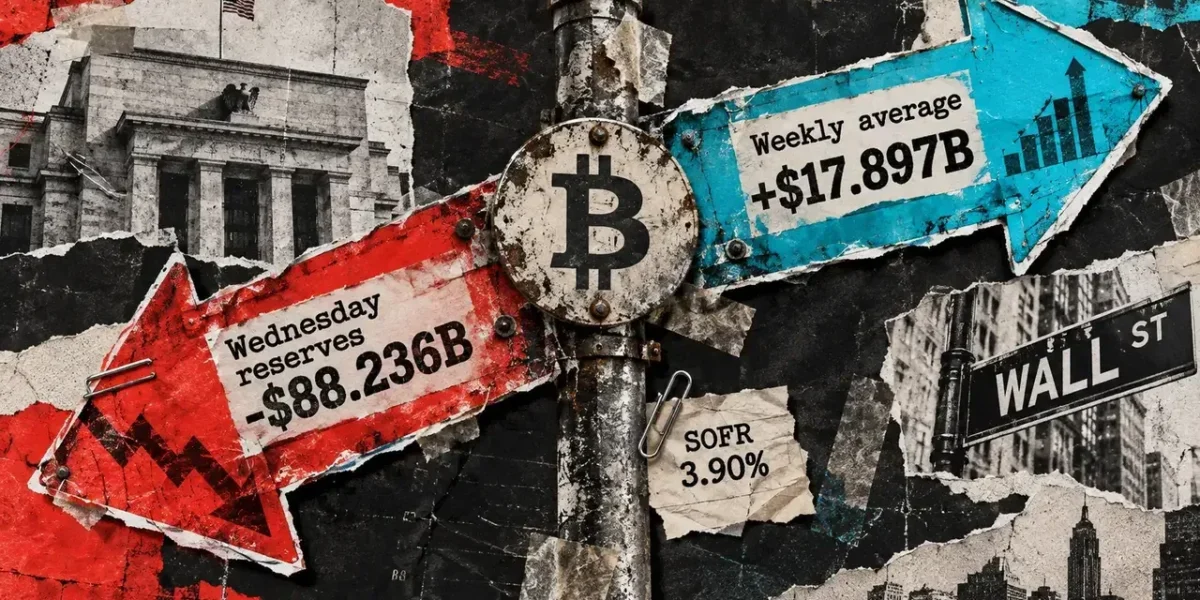
Bitcoin’s quarter-end liquidity signal shifts based on the specific reserve metric employed. According to Federal Reserve figures published Oct. 1, bank reserves decreased by $88.236 billion between the Wednesday snapshots of Sept. 23 and Sept. 30, whereas their weekly average increased by $17.897 billion.
Reserves represent the balances that banks keep at the Federal Reserve for sending and receiving payments. While these levels are crucial for dollar financing, evaluating a reserve chart alone cannot prove whether funding pressure actually impacted Bitcoin. The balance-sheet reduction is primarily explained by Treasury cash and reverse repos, which predominantly involve foreign official accounts. On Sept. 30, the median cost for Treasury-backed overnight borrowing stood at 3.90%, remaining within the band of the five most recent observations.
Consequently, the end of September provides a practical test for evaluating the metrics behind any liquidity theory. An endpoint balance, an average balance, and a funding price highlight entirely different components of the financial system. Treating these metrics interchangeably can turn the exact same week into conflicting market signals.
The Wednesday reserve series dropped from $2.969922 trillion on Sept. 23 to $2.881686 trillion on Sept. 30. In contrast, the weekly-average series grew from $2.930193 trillion to $2.948090 trillion for the respective weeks ending on those dates.
Both data points originate from the Fed’s H.4.1 release. One metric contrasts balances recorded on two specific Wednesdays, while the other contrasts averages derived from daily figures across two separate weeks. A lower final observation can easily coexist with a higher average because the two readings evaluate different time horizons.
| Measure | Sept. 23 | Sept. 30 | Change |
|---|---|---|---|
| Wednesday reserve balances | $2.969922 trillion | $2.881686 trillion | Down $88.236 billion |
| Weekly-average reserve balances | $2.930193 trillion | $2.948090 trillion | Up $17.897 billion |
The Treasury General Account (TGA), which is the federal government’s account held at the Fed, demonstrates this exact reporting discrepancy. Its Wednesday balance expanded by $36.729 billion to reach $984.046 billion, whereas its weekly average declined by $28.410 billion to settle at $948.674 billion.
Combining the Wednesday reserve drop with the average Treasury decrease merges observations taken from completely different windows. Doing so might obscure the precise cash movements an investor is trying to analyze. Any chart marked as “weekly” still demands a critical follow-up question: does each data point represent a weekly average or a balance recorded just once per week?
The endpoint captures the exact position at the quarter’s close, whereas the average reflects the general level throughout the entire week. Neither metric outlines a complete daily path or indicates the persistence of the final day’s position. When building a Bitcoin liquidity argument, selecting the timeframe alters the evidence long before any price predictions enter the conversation.
Where the Wednesday reserve decline went
The H.4.1 release published on Oct. 1, along with prior reports, provides a clear accounting bridge. Between the two Wednesday observations, factors that supply reserves dropped by $4.650 billion, while factors that absorb funds away from reserves grew by $83.586 billion. Combined, these shifts fully account for the $88.236 billion decrease in reserves.
Treasury cash played a significant role on the absorbing side, alongside total reverse repos, which climbed by $41.158 billion to reach $361.883 billion. However, the vast majority of that reverse-repo balance belonged to foreign official and international accounts, which expanded by $30.080 billion to hit $350.344 billion. The remaining “others” grouping increased by $11.078 billion to $11.539 billion.
Characterizing the entire $361.883 billion as domestic overnight reverse-repo activity misrepresents both the true counterparties and the actual scale of that facility. This distinction is also vital when reviewing charts that deduct a domestic reverse-repo series from total Fed assets, as those charts fail to capture every liability shifting within this report.
Aside from Treasury cash and reverse repos, currency in circulation ticked up by $373 million, other non-reserve deposits rose by $3.001 billion, and other liabilities and capital grew by $2.317 billion. A distinct Treasury cash-holdings line increased by $8 million. These smaller absorbing-side shifts complete the $83.586 billion increase, leaving foreign official deposits and the remaining deposit categories unchanged.
The reserve-supplying side shifted as well. Outright securities decreased by $6.491 billion, which was partially counterbalanced by an increase of $1.199 billion in repo agreements and $2.493 billion in loans. These specific movements form part of the broader accounting bridge rather than its absolute total. Treasury securities actually gained $5.829 billion while mortgage-backed securities dropped by $12.320 billion, showing that holdings did not move in unison. Furthermore, the separately presented consolidated balance sheet noted a $4.673 billion drop in total Fed assets—a distinct metric from the $4.650 billion reduction in reserve-supplying factors.
The mechanism is laid out clearly in the Fed’s breakdown of its liabilities: inflows into the Treasury account can draw down bank reserves, whereas Treasury expenditures can route balances back to banks, assuming all else remains equal. Other Fed assets and liabilities can either offset or amplify these transfers. Consequently, gross bond issuance does not equate to a withdrawal of reserves of the exact same size, and the observed expansion of the TGA cannot be attributed solely to any single debt auction using these figures alone.
For this exact reason, an $88.236 billion reduction in bank reserves does not translate to an $88.236 billion loss of capital available to purchase Bitcoin. The accounts merely clarify where balances shifted; establishing a crypto-market impact requires clear evidence of an active financing transmission channel.
Funding prices give a different test
In early checks conducted on Oct. 2, the New York Fed’s latest Secured Overnight Financing Rate (SOFR) reading still reflected data from Sept. 30. It registered at 3.90%, matching the Fed’s interest on reserve balances (IORB). The five most recent SOFR medians observed ranged tightly between 3.88% and 3.90%.
The 99th-percentile rate for Sept. 30 hit 3.99%, backed by $3.230 trillion in underlying transactions. While SOFR climbed from 3.88% the prior day, the quarter-end median matched the levels recorded on Sept. 25 and Sept. 28. This demonstrates minimal shifts in the overall median, though it leaves open the possibility of localized strain in certain market segments or among borrowers with distinct cash access.
SOFR tracks overnight borrowing collateralized by Treasury securities and is computed as a volume-weighted median. It reflects the midpoint of observed dollar volumes rather than a rate guaranteed to every individual borrower. Similarly, a 99th percentile sitting below 4% does not mean every single transaction occurred below that threshold.
Nor was there a total absence of Fed lending activity. The H.4.1 report noted $1.2 billion in outstanding repo agreements as of Sept. 30. The daily repo-purchase series independently logged $1.2 billion for that same day and zero purchases on Oct. 1. An outstanding balance and a daily transaction amount remain distinct indicators, even when their figures happen to align.
Market access provides another compelling reason to look past the median figure. The standing repo facility guidelines establish a 4.00% rate, two daily operational windows, and a $40 billion cap per eligible counterparty, per eligible security type, per operation. Because access relies heavily on counterparty and collateral qualifications, these backstop conditions cannot confirm that every market participant enjoyed immediate access to cash.
Data from Oct. 1 offered a narrower update: domestic overnight reverse-repo utilization dropped sharply from $11.539 billion down to $350 million. This indicates that the spike in the domestic facility unwound rapidly. However, it does not quantify an overall reserve rebound or prove that the foreign official pool experienced a similar decline. SOFR figures for Oct. 1 were unavailable at the time of the early Oct. 2 data snapshot.
What would establish pressure reaching Bitcoin?
CryptoSlate’s Sept. 28 settlement preview outlined a conditional evaluation of repo and Bitcoin funding activity following settlement, building upon its Sept. 21 coverage of shrinking bank reserves alongside calm repo conditions. This new reserve comparison underscores the importance of examining the metrics themselves before translating such tests into sweeping market conclusions.
Evidence pointing to a genuine dollar-funding squeeze would be far more convincing if borrowing costs stayed elevated relative to Fed benchmarks across multiple subsequent observations, showing pressure extending well beyond a single median. Tracking facility usage and access conditions would further help differentiate a temporary quarter-end accounting adjustment from persistent financing stress.
Linking these trends to Bitcoin requires an additional analytical bridge: dated exchange-level or instrument-specific funding costs, futures-basis metrics, or liquidity indicators evaluated across a comparable timeframe. Shifts in market depth, credit availability, or positioning could help substantiate that connection. Even if Bitcoin weakness coincided directly with rising repo rates, causation would remain unproven on that basis alone.
Ultimately, current reserve and SOFR metrics do not prove the presence—or the absence—of a Bitcoin financing shock. Instead, they demonstrate something much more specific: the Wednesday drop in reserves balances out against shifts elsewhere in the Fed’s accounts, the weekly average moved in the opposite direction, and the latest observed secured-cash median held steady at the IORB. Future funding costs and direct Bitcoin financing metrics will be required to either strengthen or refute the thesis that quarter-end balance-sheet fluctuations transformed into a prolonged liquidity squeeze.
Frequently Asked Questions
01What caused the drop in bank reserves?
The decline is largely accounted for by Treasury cash movements and reverse repo agreements, heavily involving foreign official accounts, alongside other smaller adjustments within the Federal Reserve’s balance sheet accounts.
02Does a drop in bank reserves mean less money to buy Bitcoin?
Not necessarily. While reserves are important for overall dollar financing, a balance-sheet decline alone does not establish a direct transmission channel or prove that liquidity pressure has negatively impacted Bitcoin markets.
03What is SOFR and why does it matter?
SOFR stands for Secured Overnight Financing Rate, which tracks overnight borrowing costs against Treasury securities. It serves as a benchmark to assess conditions in short-term dollar funding markets.